Buying a Home with a Well and Septic System in Minnesota

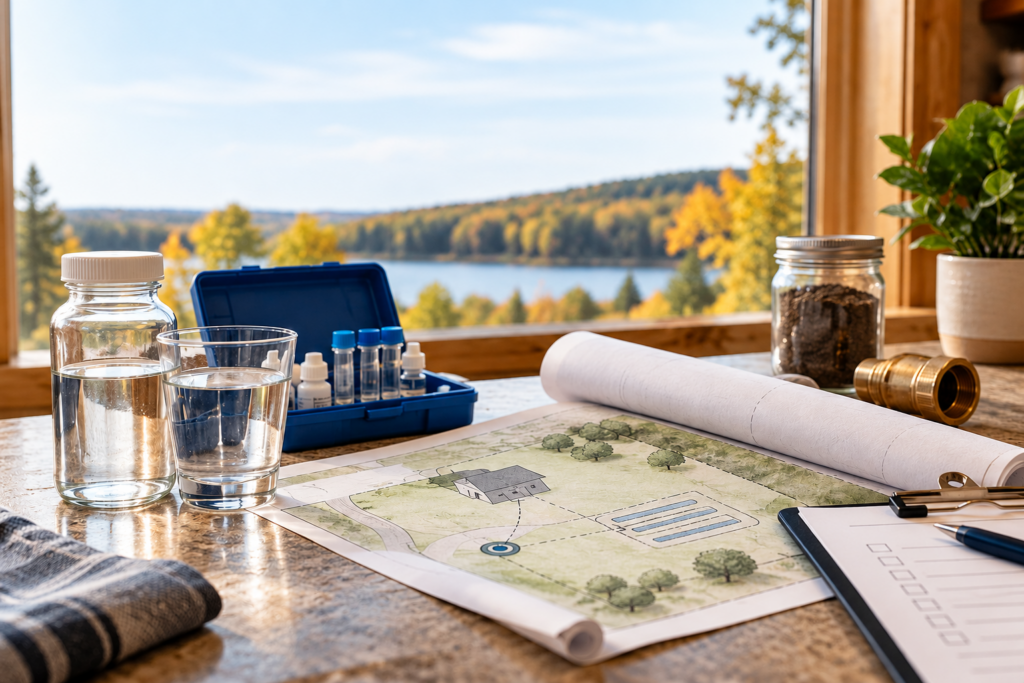
Well water samples, a water test kit and a site plan showing a home’s well and septic drainfield, with a Minnesota lake and fall trees in the background.

Head a few miles past the last sewer line in the Twin Cities metro — the wooded lots outside Prior Lake, the horse country around Independence and Medina, the acreage near Lake Elmo and Afton — and you’ll start seeing listings that say “private well” and “septic” in the details. Buying a home with well and septic in Minnesota is very doable, and plenty of people love the space and privacy that come with it. But it adds a few steps most city buyers never think about: a state well disclosure, water testing, and a septic inspection that may or may not be required depending on which county you’re buying in. Here’s what to know before you write an offer.

What Minnesota Requires When You Buy a Home with Well and Septic

Minnesota puts the disclosure burden on the seller for both systems. On the well side, the seller must give you a written well disclosure before you sign a purchase agreement. According to the Minnesota Department of Health’s well disclosure guidance, that statement includes a map of every well on the property and whether each one is in use, not in use, or sealed. At closing, a Well Disclosure Certificate is filed with the deed, along with a $54 fee that the buyer provides.

Pay close attention to that “not in use” box. If an old, unused well isn’t sealed, returned to service, or covered by a maintenance permit before closing, that responsibility passes to you. Many lenders want unused wells sealed by a licensed contractor, so it’s worth negotiating who handles it up front.

Septic works similarly. Sellers must disclose in writing how sewage is handled, where the system (and any abandoned system) is located, and whether — to their knowledge — it complies with state rules. The Minnesota Pollution Control Agency is clear, though, that a disclosure is not an inspection. It’s the seller’s best knowledge, not a professional evaluation.

Septic Compliance Inspections: It Depends on the County

This is where a lot of buyers get tripped up. Minnesota doesn’t require a septic compliance inspection at sale statewide — but many counties, cities, and townships do, especially in shoreland areas. The difference across the metro is real:

  • Washington County requires a compliance inspection when a property with septic is sold, unless a recent inspection or new-system certificate is already on file.
  • Scott County (home to the rural areas around Prior Lake) does not require one at sale — though the county notes many buyers order one anyway, and lenders sometimes require it.
  • Other counties and cities each set their own rules, so the answer for a hobby farm in Corcoran may differ from a lake lot in Chisago County.

Our advice: if you’re buying a home with well and septic, even where an inspection isn’t required, make your offer contingent on a compliance inspection by an MPCA-licensed inspector. A certificate of compliance is generally good for three years on an existing system and five years on a new one. If a system is found failing, local rules set the repair timeline, and an imminent threat to public health typically has to be fixed within months — not years.

One timely note for fall and winter buyers: frozen ground can complicate a septic evaluation. If you’re shopping between now and spring, ask early how the local county handles winter inspections so it doesn’t stall your closing.

Testing the Well Water Before You Close

Minnesota doesn’t require a water test at sale, and a standard home inspection usually doesn’t cover the well. That makes this step entirely up to you — and it’s one you shouldn’t skip. The Minnesota Department of Health recommends that private well owners test for:

  • Coliform bacteria — every year
  • Nitrate — every year
  • Arsenic, lead, and manganese — at least once

Arsenic and manganese occur naturally in groundwater across parts of Minnesota, so a one-time test during your purchase is the perfect moment to check. Use an accredited lab, and ask the seller for past test results, well construction records, and details on any water softener or treatment system. Your agent can also look the well up in the Minnesota Well Index — though wells drilled before 1974 often have no public record at all.

Budgeting for Life with a Private Well and Septic System

The trade-off for rural living is that you’re your own utility. You won’t get a city water and sewer bill, but you’ll take on maintenance that city homeowners never see:

  • Septic pumping every two to three years, plus periodic inspections.
  • Annual water testing for bacteria and nitrate.
  • Well pump and pressure tank repairs or replacement over time.
  • A septic replacement fund. A failed system — especially one that needs a mound because of soil or groundwater conditions — can run well into five figures.

If an inspection turns up a failing system, that’s not automatically a deal-breaker. It’s a negotiation point: a price reduction, a seller-paid replacement, or an escrow holdback can all work. This is exactly where an agent who’s closed rural deals before earns their keep.

FAQ: Buying a Home with Well and Septic in Minnesota

Is a septic inspection required to sell a house in Minnesota?

Not statewide. Requirements are set locally — Washington County requires one at sale, for example, while Scott County does not. Lenders may require one either way, and buyers can always make their offer contingent on one.

Does a home inspection cover the well and septic?

Usually not in any depth. Plan on a separate septic compliance inspection by an MPCA-licensed inspector and a water test through an accredited lab. A licensed well contractor can evaluate the well itself if there are concerns.

Who pays to seal an unused well?

It’s negotiable. If the seller doesn’t address an unused well before closing, the responsibility transfers to the buyer, so settle it in the purchase agreement.

Find an Agent Who Knows Rural Twin Cities Properties

A home with well and septic can give you the room, quiet, and land that’s hard to find closer in — as long as you go in with the right inspections, contingencies, and expectations. Not every agent has walked a buyer through a septic compliance report or a well disclosure certificate, and that experience matters. MinnMatch personally connects buyers with vetted local agents who know the exurban edges of the metro, from Scott County to the St. Croix Valley. See how our matching works, or get matched with an agent who’s done this before — it’s free for buyers. For more first-step guidance, visit our buyer resources.
Buying and Selling a Home at the Same Time in the Twin Cities: How to Time It in 2026

Two model homes with a calendar between them showing arrows from one house to the other, illustrating buying and selling at the same time

If you’re ready to move up, downsize, or relocate across the metro, you’ve probably hit the classic question: do you sell your current home first or buy the next one first? Buying and selling at the same time is one of the most stressful moves in real estate, and it’s also one of the most common. The good news is that the Twin Cities market in fall 2026 gives move-up buyers and sellers more room to maneuver than they’ve had in years. Here’s how to think through the timing, the financing, and the logistics so you don’t end up with two mortgages, or with no place to live.

Why Buying and Selling at the Same Time Looks Different in 2026

A few years ago, Twin Cities homes routinely sold in a weekend, and buyers who needed to sell first were often shut out. That’s changed. According to Minnesota Realtors’ August 2026 report, statewide inventory reached a seven-year high, and Twin Cities homes averaged about 45 days on market. Sellers are still getting strong prices, with a metro median of roughly $405,000 and homes selling for about 98% of list price, but buyers have more choices and more time.

For anyone selling one home and buying another, that balance cuts both ways:

  • On the buying side, sellers are more open to offers with a home-sale contingency than they were in 2021 or 2022, especially on homes that have been listed for a few weeks.
  • On the selling side, you can’t count on a bidding war the first weekend, so your plan needs to allow for a month or more of market time.
  • On the financing side, 30-year rates averaged 7.40% in early October per Freddie Mac’s weekly survey, which makes carrying two mortgages, even briefly, more expensive.

Sell First or Buy First? Weighing Your Two Paths

There’s no universally right answer. The best order depends on your equity, your cash reserves, how quickly homes are moving in your neighborhood, and how much uncertainty you can stomach.

Option 1: Sell First, Then Buy

Selling first is the lower-risk financial move. You know exactly how much equity you’re walking away with, you’ll never carry two mortgages, and you can make a clean, non-contingent offer on your next home, which still carries weight in desirable areas like Edina or Minnetonka.

The trade-off is housing. If your home sells before you find the next one, you’ll need a place to land. Common solutions include:

  • A rent-back agreement, where you stay in your sold home for a few weeks after closing while paying the buyer an agreed daily or monthly rate.
  • A longer closing date, such as 45 to 60 days, negotiated up front to give yourself shopping time.
  • A short-term rental or family stay, plus storage. It’s less convenient, but it removes all timing pressure from your purchase.

Option 2: Buy First, Then Sell

Buying first means one move, no temporary housing, and the freedom to grab the right house when it appears. It’s also the riskier path, because you may own two homes for a while. Most Twin Cities buyers who go this route use one of three tools:

  • A home-sale contingency, which makes your purchase dependent on selling your current home by a set date. It protects you, but it weakens your offer, so it works best on homes that have sat for a while.
  • A bridge loan, a short-term loan secured by your current home that lets you tap your equity for the down payment before you sell. Bridge loans typically carry higher rates and fees than a standard mortgage, so they’re best for a short gap.
  • A HELOC, or home equity line of credit, opened on your current home before you list. It’s often cheaper than a bridge loan, but it needs to be in place before your home goes on the market.

Before committing to either path, talk with a lender about whether you qualify to carry both payments, even for a month or two. That single answer often decides the order for you.

A Realistic Twin Cities Timeline for Lining Up Both Closings

The goal for most people is a same-day or back-to-back closing: sell in the morning, buy in the afternoon, and move once. Buying and selling at the same time this way is very doable in Minnesota with the right planning. Here’s a typical sequence:

  1. Get pre-approved and price your home (weeks 1–2). Know what you can buy and what your current home is realistically worth. A solid market analysis keeps you from planning around a number the market won’t pay.
  2. Handle city requirements and prep (weeks 2–4). Minneapolis, St. Paul, and several other metro cities require a point-of-sale or truth-in-housing evaluation before you list. Schedule it early so it doesn’t stall your listing.
  3. List your home and start touring (weeks 4–6). With metro homes averaging about six weeks on market, shopping while you’re listed is usually the sweet spot.
  4. Negotiate dates on both deals. Once you have a purchase agreement on your sale, write your offer with a matching closing date, or ask your buyer for a short rent-back as a cushion.
  5. Close and move. Your title company and lender coordinate the funds so your sale proceeds can flow straight into your purchase.

One Minnesota-specific note: if you’re doing this in late fall or winter, build in a buffer. Moving in a January cold snap or around holiday closures at title companies and lenders can push dates. If you’re weighing a winter listing, our seller resources walk through what to expect.

Buying and Selling at the Same Time: Common Questions

Can I close on my sale and purchase on the same day in Minnesota?

Yes. Same-day closings are common in the Twin Cities. Typically the sale closes first, and the proceeds are wired to the closing for your purchase. Your agent, lender, and title company need to coordinate tightly, so let everyone know early that you’re planning back-to-back closings.

Will sellers accept an offer that’s contingent on selling my home?

More often than they used to. With inventory up and homes taking longer to sell, many Twin Cities sellers will consider a home-sale contingency, especially if your home is already listed, priced well, or under contract. Newer listings in high-demand neighborhoods may still favor non-contingent buyers.

Should I use the same agent for both my sale and my purchase?

It usually helps. One agent who manages both sides can line up dates, negotiate rent-backs, and keep both transactions moving toward the same finish line. If your sale and purchase are in different parts of the metro, make sure that agent knows both markets well.

The Right Agent Makes the Timing Work

Buying and selling at the same time comes down to coordination: pricing your current home correctly, writing an offer that fits your timeline, and keeping lenders, title companies, and the other parties on the same schedule. That’s where an experienced local agent earns their keep. Someone who has juggled dozens of these moves knows when a contingency will fly, when to push for a rent-back, and how to protect you if one side slips.

If you’re planning a move-up, a downsize, or a cross-metro move, MinnMatch can connect you with a vetted Twin Cities agent who handles both sides of the transaction regularly. It’s free, and every match is made by a real person, not an algorithm. See how MinnMatch works, or find your agent match today. For the latest local numbers, you can also check the Minneapolis Area Realtors market data.

Radon and Buying a Home in Minnesota in 2026: Testing, Disclosure Rules & Mitigation Costs

Continuous radon monitor on a Minnesota basement counter beside a radon test report, floor plan, and white mitigation pipe

If you’re buying a home anywhere in the Twin Cities this year, radon belongs on your checklist right next to the furnace, the roof, and the foundation. Radon in Minnesota isn’t a rare, worst-case problem. It’s common, it’s invisible, and it shows up in brand-new builds in Plymouth just as easily as 1920s bungalows in South Minneapolis. The good news is that it’s easy to test for, Minnesota has clear disclosure rules, and fixing it is usually a one-day job. Here’s what every buyer (and seller) should know in 2026.

Radon at a Glance

2 in 5

Minnesota homes with radon at levels that pose a significant health risk

4 pCi/L

EPA action level where mitigation is recommended

48 hrs

Minimum length of a real estate radon test

$1,500–$3,000

Typical cost range for a mitigation system

Source: Minnesota Department of Health

Why Radon in Minnesota Is a Bigger Deal Than Most Buyers Expect

Radon is a naturally occurring radioactive gas that seeps up from the soil and into homes through foundation cracks, sump pits, floor drains, and gaps around pipes. You can’t see it, smell it, or taste it. Our glacial soils make this state a hot spot: according to the Minnesota Department of Health, more than two in five homes here have radon at levels that pose a significant health risk, and the average level statewide runs more than three times the national figure.

Why does that matter? Radon is the leading cause of lung cancer among nonsmokers. And Minnesota living makes exposure worse in a very specific way: we keep our homes sealed up tight for five or six months a year, and many of us spend a lot of that time in finished basements, which is exactly where radon levels tend to be highest. Your neighbor’s test results also tell you very little. Two houses on the same Edina block can test completely differently, so the only way to know is to test the home you’re buying.

What Minnesota’s Radon Disclosure Rules Actually Require

Since January 1, 2014, the Minnesota Radon Awareness Act (Minn. Stat. § 144.496) has required sellers of residential property to disclose what they know about radon before a purchase agreement is signed. Those rules are unchanged heading into 2026. In writing, the seller must share:

  • Whether the home has ever been tested for radon
  • The most current test records and results
  • Any mitigation or remediation that’s been done
  • Information and documentation on any installed mitigation system
  • A required radon warning statement, plus a copy of the MDH publication Radon in Real Estate Transactions

Here’s the part that surprises a lot of buyers: the law does not require anyone to test. Sellers only have to disclose what they already know. If they’ve never tested, the disclosure simply says so. If a seller knowingly hides radon information, a buyer can take legal action within two years of closing. Also note that some sales are exempt, including foreclosures and transfers to heirs, so if you’re eyeing a bank-owned or estate property, you may get no radon disclosure at all. For more on the broader disclosure picture, our buyer resources walk through what to expect in a Minnesota transaction.

How to Test for Radon When You’re Buying a Home

Because testing isn’t automatic, it’s up to you to build it into your offer, usually alongside your home inspection contingency. MDH’s real estate radon guidance lays out how a proper test should be done:

  • Use a licensed pro. Under the Minnesota Radon Licensing Act, anyone testing a home they don’t own or rent must be licensed by MDH. Many home inspectors carry the license and can run the test during your inspection.
  • Test for at least 48 hours. That means a calibrated continuous radon monitor or two short-term kits placed side by side.
  • Keep the house closed up. Windows and doors stay shut except for normal coming and going, with heating or cooling running as usual.
  • Test the lowest livable level. In most Twin Cities homes, that’s the basement.

Timing matters. A 48-hour test plus results can eat up a good chunk of a short inspection window, so get it scheduled the day your offer is accepted. And yes, test new construction too. Minnesota has required new homes to be built radon-resistant since 2009, but the standard setup is a passive pipe with no fan. It helps, but it doesn’t guarantee a low reading. The upside is that if levels come back high, adding a fan to an existing passive system is usually simpler and cheaper than starting from scratch.

Selling? MDH notes that sellers can benefit from testing before listing. A pre-listing test lets you mitigate on your own timeline instead of negotiating under pressure mid-deal. Our seller resources cover other ways to get ahead of inspection surprises.

Radon Mitigation Costs in Minnesota (and Who Pays)

If the test comes back at or above 4 pCi/L, MDH recommends installing a mitigation system. Between 2 and 4 pCi/L, it’s worth considering. According to MDH’s mitigation guidance, costs generally range from $1,500 to $3,000, depending on how the home is built and which type of system it needs:

  • Sub-slab suction – the most common setup for basement and slab homes
  • Drain tile suction – uses an existing drain tile system to pull radon away
  • Sub-membrane – for crawl spaces, sealing a membrane over the soil

All three work the same basic way: a fan runs continuously, pulling radon from beneath the home and venting it out a pipe above the roofline. A well-installed system should bring levels below 4 pCi/L, and often below 2. Mitigators must be MDH-licensed and attach an MDH tag to finished systems, and most installs need an electrical permit for the fan. Once it’s running, wait at least 24 hours and retest to confirm it’s working.

Who pays is negotiable, and a high radon result rarely needs to kill a deal. Common outcomes include the seller installing a system before closing, a closing credit so the buyer can hire their own mitigator, or a price adjustment. If the home already has a system, ask for the documentation, look for the MDH tag, and know that MDH offers a free inspection for systems installed after June 2020.

Radon in Minnesota: Quick Answers to Common Questions

Do Minnesota home sellers have to test for radon?

No. Sellers must disclose any radon testing, results, and mitigation they know about, and provide the required MDH publication, but they aren’t required to test. Testing is the buyer’s call.

Should I walk away from a house with high radon?

Usually not. Elevated radon is common here and is one of the more predictable fixes in a home purchase. A typical system costs $1,500 to $3,000 and can be installed quickly, so most buyers negotiate a fix or credit rather than walking.

Do newer homes still need a radon test?

Yes. Homes built since 2009 include radon-resistant features, but most use a passive system without a fan. Testing tells you whether that’s enough or whether a fan upgrade makes sense.

The Right Agent Makes Radon a Non-Event

Handled well, radon is a line item, not a crisis. The difference usually comes down to your agent: someone who writes testing into your offer, keeps the inspection timeline on track, and knows how to turn a high reading into a fair fix or credit without derailing the deal. Experienced local agents deal with radon in Minnesota on nearly every transaction, from Prior Lake to Wayzata.

That’s exactly the kind of agent MinnMatch connects you with. We personally match buyers and sellers with vetted Twin Cities agents who know the local details, and it’s free. See how our matching works, or find your agent and walk into your next home purchase with one less thing to worry about.

What Does a Real Estate Agent Actually Do? A Minnesota Buyer’s Complete Guide

A Minnesota real estate agent meeting with home buyers at a table to discuss the home buying process

If you’re thinking about buying a home in the Twin Cities and wondering whether you really need a real estate agent — or what one even does all day — you’re not alone. It’s one of the most common questions first-time buyers ask. The short answer is that a good buyer’s real estate agent does a lot more than unlock doors and hand you paperwork. In a competitive market like Minneapolis–St. Paul, having the right agent in your corner can make the difference between landing your dream home in Eden Prairie and watching it go to someone else. Here’s a plain-English breakdown of what a buyer’s agent actually does for you from start to finish.

They Start With Your Goals, Not a List of Listings

Before a good Minnesota buyer’s agent sends you a single Zillow link, they sit down and actually listen. That means a real conversation about your budget, your must-haves, your commute, your school district priorities, and the kind of neighborhood where you’d genuinely be happy. Are you drawn to walkable South Minneapolis bungalows or newer construction in Woodbury? Do you need a home office, a big yard, or easy highway access?

This intake process matters because it shapes everything that follows. A skilled agent will also help you get clear on your financing situation early — connecting you with lenders if needed, reviewing your pre-approval, and making sure you’re searching in a realistic price range before you fall in love with something out of reach.

They Know the Twin Cities Market in Ways Algorithms Don’t

Real estate search tools are everywhere, but they don’t tell you that one block in Plymouth feeds a different elementary school than the next, or that a listing’s “updated kitchen” actually means laminate counters and builder-grade cabinets. Your agent brings local knowledge that no app can replicate.

Experienced Twin Cities agents track inventory levels, average days on market, and neighborhood pricing trends week to week. They know which Edina zip codes tend to see multiple offers within 48 hours, and which pockets of Maple Grove are quietly undervalued. They’ll also monitor the Minneapolis Area Realtors monthly market reports and share relevant data with you as you search.

Beyond the data, agents have access to the Regional MLS — and sometimes hear about listings before they go live. That off-market and pre-market intel can be invaluable when inventory is tight.

They Represent You Legally — and Have a Fiduciary Duty to You

This is where a lot of buyers are surprised: when you sign a Buyer Representation Agreement with a Minnesota agent, that agent is legally required to act in your best interest. Under Minnesota Statute 82.67, a buyer’s broker owes you fiduciary duties — including loyalty, confidentiality, disclosure of material facts, and a legal obligation to put your interests first.

This means your agent can’t share your budget ceiling with the seller’s agent. They have to tell you if they learn something about the property that could affect your decision. And they have to advocate for you — not for the commission, not for the seller, not for a quick close.

As of August 2024, Minnesota buyers are now required to sign a written Buyer Representation Agreement before touring homes with an agent. This change — part of the national NAR settlement — made compensation conversations more transparent, and it reinforced what was already true: your agent works for you.

They Write and Negotiate Offers Strategically

When you find a home you want to buy, your real estate agent becomes your strategist. This is one of the most important things they do. Writing a strong offer in the Twin Cities isn’t just about the price — it involves structuring contingencies, deciding on an earnest money amount, choosing a closing date that appeals to the seller, and sometimes writing an escalation clause to beat out competing bids.

Your agent will pull recent comparable sales (called “comps”) to help you decide what the home is actually worth — and whether the asking price is fair, high, or a bargain. In hot markets like Edina or Wayzata, where desirable homes regularly attract multiple offers, that pricing analysis and offer strategy can directly save or cost you tens of thousands of dollars.

And once you’re under contract, negotiation doesn’t stop. If the inspection reveals issues — a cracked heat exchanger, outdated electrical, a leaking roof — your agent handles the repair requests or credits, keeping the conversation professional and focused on your interests.

They Coordinate the Whole Transaction Behind the Scenes

Buying a home involves a small army of professionals: lenders, inspectors, title companies, appraisers, and sometimes contractors. Your buyer’s agent manages all of it. They schedule your inspection, track contingency deadlines, communicate with the listing agent, follow up with your lender on the appraisal, and make sure nothing slips through the cracks.

Minnesota real estate transactions have a lot of moving parts — purchase agreements, financing contingencies, title searches, final walk-throughs — and there are legally binding deadlines throughout. A missing signature or a missed deadline can cost you your earnest money or, in a worst case, the home entirely. Your agent keeps the timeline on track so you don’t have to stress about what’s due when.

They also serve as your translator. Purchase agreements and title documents can be dense. Your agent explains what you’re signing — and flags anything that looks unusual or worth asking your attorney about.

What About the Cost? Here’s What Minnesota Buyers Need to Know

Under the updated commission rules that took effect in August 2024, buyer’s agent compensation is now negotiated directly and disclosed upfront in your Buyer Representation Agreement — rather than being bundled invisibly into the transaction. In most Twin Cities deals, buyers can still request that the seller contribute toward buyer’s agent compensation as part of the purchase offer, and many sellers agree to it.

The bottom line: working with a buyer’s agent is often effectively free to you when you negotiate seller concessions — and even when it isn’t, the guidance on pricing, strategy, and negotiation typically returns far more value than the cost. For first-time buyers especially, having an experienced professional in your corner is worth it.

If you’re exploring down payment assistance, Minnesota Housing Finance Agency (MHFA) also offers programs that can reduce upfront costs — and a good agent will know which ones apply to your situation.

The Right Agent Makes All the Difference

Not all buyer’s agents are equal. Experience level, local specialization, communication style, and negotiating skill vary widely. An agent who mostly works the suburbs may not know South Minneapolis the way someone who’s sold there for a decade does. An agent who handles volume may not give you the hands-on attention a first-time buyer needs.

That’s exactly the problem MinnMatch was built to solve. We match Twin Cities buyers with vetted, local agents based on your specific needs, your target neighborhoods, and your buying timeline — completely free of charge. No cold calls, no algorithm-assigned strangers, no guesswork. Just a personally matched agent who knows your market and is ready to work for you.

Whether you’re buying in Eden Prairie, Plymouth, Minnetonka, or anywhere else in the metro, find your agent through MinnMatch and start your home search with a professional who’s genuinely in your corner.

Ready to Find Your Agent?

MinnMatch connects Twin Cities buyers with vetted local agents — personally matched, always free.

Find My Agent

Pre-Approval in 2026: What Minnesota Buyers Need to Know Before House Hunting

Mortgage pre-approval documents with house keys, a green approval checkmark, and a Minnesota state outline, with a Twin Cities suburban home in the background


Minnesota Buyer’s Guide · 2026

Mortgage Pre-Approval in Minnesota: What Every Buyer Needs to Know Before House Hunting in 2026

Interest rates have shifted. Lending rules have changed. Here's what every Twin Cities buyer should know before stepping into a single open house.

📅 May 2026
🕐 8 min read
MinnMatch Editorial Team

Mortgage pre-approval in Minnesota isn't just a formality — it's the foundation of your entire home buying strategy in 2026. Whether you're targeting a craftsman in South Minneapolis, a townhome in Plymouth, or a lakefront property near Wayzata, sellers expect a verified pre-approval letter before they'll take your offer seriously.

If you're planning to buy a home in Minnesota this year, skipping pre-approval doesn't just slow you down — it can cost you the home entirely. The window between finding a home and losing it to another buyer can be days, sometimes hours.

Here's everything you need to know about mortgage pre-approval in Minnesota — specifically in the Twin Cities and greater Minnesota market — straight from the team at MinnMatch.


Why Mortgage Pre-Approval in Minnesota Matters More Than Ever in 2026

The Minnesota housing market has matured significantly since the volatility of 2022–2023. Competition in desirable neighborhoods — Eden Prairie, Edina, North Loop, Rosemount — remains intense, and sellers are increasingly savvy. In most multiple-offer situations, a seller won't even glance at an offer without a pre-approval letter attached.

But beyond winning offers, mortgage pre-approval gives you clarity. It sets a realistic ceiling on what you can afford, protects you from emotional overreach, and positions you as a serious buyer. According to Minneapolis Area REALTORS®, the majority of accepted Twin Cities offers include a verified pre-approval letter — not just a pre-qualification.

74%
of accepted offers in the Twin Cities had pre-approval letters attached in 2025

11 days
average time on market for single-family homes in metro Minnesota (early 2026)

3–5
competing offers on popular listings in sought-after Twin Cities suburbs


Pre-Qualification vs. Pre-Approval: Know the Difference

These two terms are often used interchangeably, but they're not the same — and in a competitive Minnesota market, the difference matters enormously.

Factor Pre-Qualification Pre-Approval
What it involves Self-reported income & assets, no verification Full credit check, income verification, document review
Time to complete Minutes (online form) 1–5 business days
Seller confidence Low — often dismissed High — accepted by virtually all sellers
Rate lock available? No Often yes, depending on lender
Best used for Early budgeting exploration Active house hunting, submitting offers

⚠️

Don't be misled by online pre-qual tools. Many mortgage websites offer instant “pre-qualification” that takes 90 seconds and checks no financial data. These letters carry little to no weight with Minnesota sellers in 2026. Make sure you're getting a true mortgage pre-approval from a licensed Minnesota lender.


What Minnesota Mortgage Lenders Are Looking at in 2026

Lending standards have stabilized since the turbulence of 2023, but lenders are still thorough. Here's what you'll need to have in order before applying for mortgage pre-approval in Minnesota:


Documents You'll Need to Gather

Two years of tax returns — W-2s or 1099s. Self-employed buyers typically need two full years of filed returns plus a year-to-date profit & loss statement.

Recent pay stubs — typically the last 30 days. If you've changed jobs recently, be prepared for extra scrutiny.

Bank statements (2–3 months) — lenders want to see your down payment is in your account and has been there long enough to be considered “seasoned.”

Credit report authorization — your lender will pull this directly, but review your own credit beforehand for any errors or surprises.

Photo ID — government-issued ID for all borrowers on the application.

Gift letter (if applicable) — if any portion of your down payment is a gift from family, lenders require a signed letter confirming it doesn't need to be repaid.

Asset statements — 401(k), IRA, brokerage accounts, etc. These may count toward your reserves.

Key Financial Metrics Lenders Evaluate

Debt-to-income ratio (DTI): Most conventional loans want your total monthly debt payments — including the new mortgage — to be below 43–45% of your gross monthly income. FHA loans can go slightly higher. A lower DTI strengthens your application significantly.

Credit score: Conventional loans typically require a minimum 620, though you'll see better interest rates at 740+. FHA loans allow scores as low as 580 with a 3.5% down payment. In Minnesota's competitive market, a strong credit profile can also help you negotiate better terms.

Down payment: Conventional loans now allow as little as 3% down for first-time buyers. FHA is 3.5%. VA and USDA loans — applicable to eligible buyers in certain Minnesota rural areas — remain zero-down options. More down typically means lower monthly payments and no private mortgage insurance (PMI).


Minnesota Home Buyer Programs That Work Alongside Pre-Approval

Minnesota has robust homebuyer assistance programs that can significantly reduce the upfront cost of buying a home. These are worth exploring before you commit to a lender — and many of them integrate directly into the mortgage pre-approval process. Minnesota Housing administers the state's primary programs, and your lender should be familiar with all of them.

1

Minnesota Housing Start Up Loan

Designed for first-time buyers, this program offers below-market interest rates and down payment assistance of up to $17,000. Income and purchase price limits apply, but they're generous enough for many Twin Cities buyers.

2

Step Up Program

For repeat buyers or those with higher incomes who don't qualify for Start Up. Provides competitive rates and optional down payment assistance. Particularly useful in suburban markets like Plymouth, Woodbury, or Lakeville.

3

Community Homeownership Programs

Several metro counties — including Hennepin and Ramsey — offer local down payment assistance grants and forgivable loans for buyers purchasing in specific neighborhoods or income brackets.

4

Veteran-Specific Programs

Minnesota Veterans Home Loan offers a low-interest mortgage alongside federal VA loan benefits. If you're a veteran buying in Minnesota, using both programs together can dramatically reduce costs.

MinnMatch Pro Tip

Many Minnesota buyers leave money on the table by not asking their lender about state and county assistance programs upfront. A great local lender — one familiar with Minnesota Housing programs — will proactively walk you through these options. When we match buyers with agents, we can also connect you with vetted local lenders who know these programs inside and out.


How Long Does Pre-Approval Last — and What Can Invalidate It?

A typical mortgage pre-approval letter is valid for 60 to 90 days. After that, your lender will need to re-verify your financial information before the letter can be used. In a slower market, this might not matter much. In Minnesota's current market, where good homes move fast, you'll want to time your pre-approval carefully.

What Can Kill Your Minnesota Pre-Approval After You Get It

Getting pre-approved is step one. Protecting it is step two. These are the most common mistakes buyers make that can invalidate or weaken their pre-approval before closing:


Things to Avoid After Getting Pre-Approved

Opening new credit cards or taking out any new loans

Making large purchases (furniture, a car, appliances) before closing

Switching jobs or becoming self-employed

Moving money between accounts without documentation

Missing any bill payments or letting accounts go delinquent

Co-signing any loan for another person


How to Choose the Right Minnesota Mortgage Lender for Pre-Approval

Not all lenders are created equal — and this is especially true in Minnesota, where familiarity with local programs and market timing can make a meaningful difference. The Consumer Financial Protection Bureau recommends comparing at least three lenders before committing to ensure you're getting competitive terms.

Local vs. national lenders: Big national banks offer scale, but local Minnesota lenders and credit unions — like Affinity Plus, Firefly Credit Union, or Twin Cities-based mortgage brokers — often have more flexibility, faster turnaround, and deeper knowledge of state programs.

Mortgage brokers vs. direct lenders: A mortgage broker shops your file across multiple lenders to find the best rate. A direct lender funds the loan themselves. Brokers can be especially useful for buyers with non-standard income (freelancers, business owners, commission-based earners).

Get multiple quotes: Rate differences of even 0.25% compound meaningfully over 30 years. Rate shopping within a 14–45 day window counts as a single credit inquiry, so comparing lenders won't hurt your score.

Ask the right questions: What loan programs are you familiar with? What's your average time from application to clear-to-close? Do you offer rate locks, and for how long? What are your fees, and are they negotiable?


The Right Order of Operations for Minnesota Home Buyers

Many buyers get this backwards. Here's the sequence that actually sets you up for success — from securing your Minnesota mortgage pre-approval to finding the right agent and closing on your home:

1

Review your credit and finances

Pull your credit reports from all three bureaus (free at AnnualCreditReport.com). Dispute any errors. Pay down high-utilization accounts if you can. Give yourself 60–90 days before applying if you need to clean things up.

2

Get pre-approved — not just pre-qualified

Apply with at least two Minnesota mortgage lenders. Get a formal pre-approval letter with a specific dollar amount. This is what sellers and their agents want to see.

3

Find the right buyer's agent

With pre-approval in hand, now you're ready to work with an agent. This order matters — a great agent will want to know your pre-approval amount to properly guide your search. MinnMatch matches Minnesota buyers with vetted local agents at no cost.

4

Start your search strategically

With pre-approval and a trusted agent in place, you can move fast when the right home comes along — and in Minnesota's market, speed often determines who wins.

The MinnMatch Difference

Most buyers find their agent before getting pre-approved — but the best agents actually prefer you to have it first. At MinnMatch, when we match you with a vetted Twin Cities buyer's agent, we'll also help you think through the pre-approval process so you're genuinely ready to compete. It's the kind of guidance that comes from a human matchmaker, not an algorithm.

MinnMatch

Ready to Find Your Agent — and Your Home?

MinnMatch personally matches Minnesota buyers and sellers with the right local agent for their situation. No algorithms. No ads. Just a free, human-powered introduction to a vetted professional who knows your market.

Get Matched — It's Free →

MM
MinnMatch Editorial Team
Minnesota Real Estate Guidance · minnmatch.com