Should You Buy a Home in the Twin Cities Before Year-End 2026? Here’s What to Consider

Snow-dusted model house, keys, and a December 2026 calendar on a wooden table, representing a year-end home purchase

Every fall, the same question starts popping up around Twin Cities kitchen tables: should we buy a home before year-end, or wait for spring? In 2026, that question has a few new wrinkles. Mortgage rates just climbed to their highest level in nearly three years, inventory is up, and a lot of buyers have quietly stepped back. That combination cuts both ways. For some households it’s a genuine opening; for others, waiting really is the smarter move. Here’s an honest look at both sides so you can decide what makes sense for you.

Twin Cities Market Snapshot · Fall 2026

11,970

Homes for sale, up 9.1% from a year ago

–15.9%

Weekly pending sales vs. the same week last year

7.28%

Average 30-year fixed rate (Oct. 1, 2026)

$395,000

12-month median sales price, up 1.5%

Sources: Minneapolis Area REALTORS®/NorthstarMLS (inventory and pending sales for the week ending Sept. 12, 2026; median price for Sept. 2025–Aug. 2026); Freddie Mac Primary Mortgage Market Survey.

Where the Twin Cities Market Stands Heading Into Q4

The biggest story this fall is rates. According to Freddie Mac’s weekly survey, the average 30-year fixed rate hit 7.28% on October 1, up from 6.71% just four weeks earlier and the highest reading since late 2023. On a $395,000 home with 10% down, that jump alone adds roughly $135 a month to principal and interest.

Buyers have noticed. Minneapolis Area REALTORS® reports that showing activity was down 12.6% year over year in late September, with the busiest price band ($300K–$400K) down more than 16%. Meanwhile, sellers keep listing. More homes and fewer shoppers is the textbook recipe for buyer leverage, and that’s exactly what’s happening across much of the metro. Homes are also taking a bit longer to sell. Redfin’s Minneapolis data shows homes selling in about 20 days on average, compared to 18 a year ago.

Prices, though, haven’t cracked. The metro median is still up modestly year over year, and well-priced homes in popular suburbs like Plymouth and Edina still move quickly. So this isn’t a fire sale. It’s a market where patient, prepared buyers have more room to negotiate than they’ve had in years. For deeper monthly numbers, our market insights page tracks the trends as they come in.

5 Reasons to Buy a Home Before Year-End

If your finances are solid and you’ve been planning to move anyway, the next 90 days have some real advantages.

1

You’ll have more negotiating power

With pending sales down and inventory up, many sellers are open to price reductions, inspection repairs, or covering closing costs. Those conversations were hard to have in a bidding war.

2

Seller credits can soften high rates

Instead of a lower price, some buyers ask for a seller-paid rate buydown. Depending on the structure, that can trim your monthly payment more than a price cut of the same size. Your lender can run the numbers both ways.

3

Fall and winter sellers tend to be motivated

People listing in October through December usually have a reason: a job relocation, a new home already purchased, a life change. Motivated sellers are often more flexible on terms and timing.

4

You’ll beat the spring crowd

Twin Cities buyer activity reliably picks back up in March and April. If rates ease at all over the winter, the buyers who sat out this fall will come back at once, and competition will return with them.

5

You can refinance later, but you can’t renegotiate the price

If rates fall in 2027, a refinance could lower your payment. The price and concessions you negotiate now are locked in for good. That said, never buy counting on a refinance. Make sure today’s payment works on its own.

When Waiting Until Spring 2027 Makes More Sense

Urgency isn’t a reason by itself, and not everyone should buy a home before year-end. Holding off is often the right call if any of these sound like you:

The payment at 7%+ would stretch you thin. If the monthly number only works with zero cushion for a furnace repair or a January heating bill, give yourself more time to save or pay down debt. Minnesota winters have a way of finding the weak spots in a budget.

Your job or income is in flux. A new role, an upcoming raise, or a pending move can all change what you qualify for. It’s usually wise to let that settle first.

You need a specific home type that’s scarce right now. Lakefront properties, homes in a particular school district, or one-level living in a specific suburb can have thin selection in late fall. Spring brings more listings, even if it also brings more competition.

You’re not sure where you want to live yet. Use the winter to tour neighborhoods, compare commutes, and explore our community guides. Buying the right home a few months later beats buying the wrong one in December.

A Quick Gut-Check Before You Decide

Before you commit to a timeline, sit down with these questions. If you can answer yes to most of them, a year-end purchase is probably worth pursuing:

  • Do I have a current mortgage pre-approval at today’s rates, not last summer’s?
  • Is the monthly payment comfortable, with room left for savings and surprises?
  • Do I plan to stay at least five years, so price swings and closing costs even out?
  • Can I handle a move during the holidays or the first stretch of winter?
  • Do I know which neighborhoods and price range actually fit my life?

If a few of those are still question marks, that’s fine. It just means your timeline is spring, and you can use the next few months to get ready. Our buyer resources are a good place to start.

FAQ: Buying a Home Before Year-End in the Twin Cities

Is it too late to close on a home by December 31, 2026?

Not yet. Most financed purchases take 30 to 45 days from accepted offer to closing. If closing in 2026 matters to you, aim to have an accepted offer by mid-November. That leaves breathing room for appraisals, inspections, and holiday-season scheduling delays at lenders and title companies.

Should I wait for mortgage rates to come down before buying?

Nobody can reliably predict rates, and they’ve moved sharply in both directions this year. Waiting for lower rates can mean facing more competition and firmer prices in spring. The better question is whether the payment works for you today. If it does, and you find the right home, timing the rate market matters less than you’d think.

Are there tax advantages to closing before year-end?

Possibly. Some buyers can deduct prepaid mortgage interest, points, and property taxes paid at a December closing on their 2026 return, but it depends on whether you itemize. Talk with a tax professional before letting taxes drive your timeline.

The Right Timing Starts With the Right Agent

Whether you decide to buy a home before year-end or plan for a spring 2027 move, the decision gets easier with someone in your corner who knows your target neighborhoods block by block. A good local agent can tell you which sellers are negotiating, where concessions are on the table, and whether a home is priced right for today’s market, not last spring’s.

That’s what MinnMatch is here for. We personally match Twin Cities buyers with vetted local agents who fit their goals, timeline, and communication style. It’s free, there’s no pressure, and you’re never handed off to an algorithm. See how it works, or find your agent match today and start the conversation on your terms.
The Most Common Home Buying Mistakes in the Twin Cities in 2026 — And How to Avoid Them

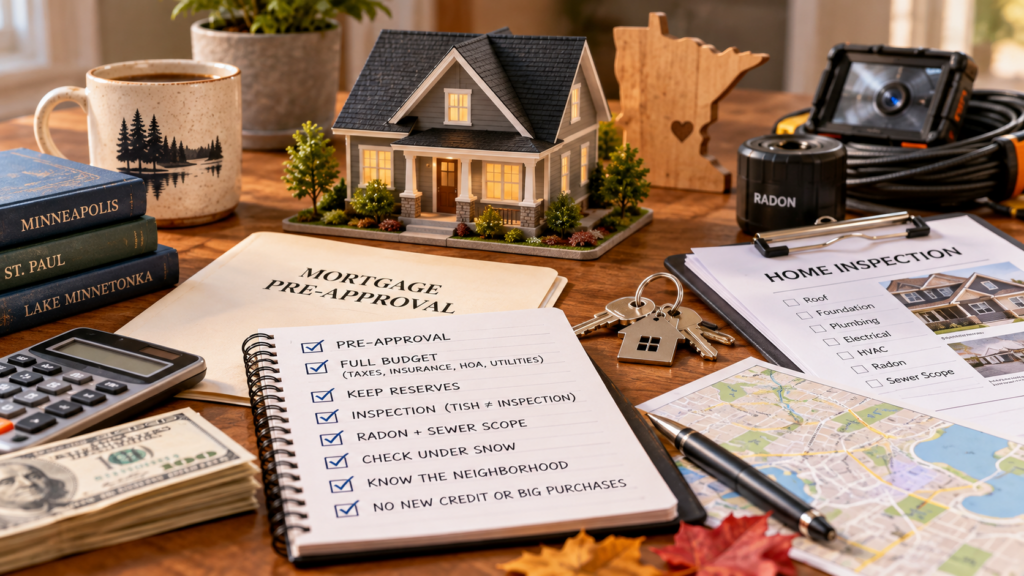
Home buying checklist for Twin Cities buyers with mortgage pre-approval, inspection form, radon test, keys, and Minnesota map

Buying a home in the Twin Cities is one of the biggest financial moves most of us will ever make, and in 2026 the margin for error is thinner than it’s been in years. Mortgage rates just crossed 7%, prices keep inching up, and the metro’s neighborhoods are moving at wildly different speeds. The good news? Most home buying mistakes are completely avoidable once you know where people tend to trip up. Here are the eight we see most often across Minneapolis, St. Paul, and the suburbs, plus exactly how to sidestep each one.

Money Mistakes: The Home Buying Mistakes That Start Before Your First Showing

The costliest errors usually happen at the kitchen table, long before you walk into an open house in Plymouth or Highland Park. Get the numbers right first and every decision after gets easier.

1

Shopping before you have a real pre-approval

An online “pre-qualification” isn’t the same as a lender actually reviewing your income, assets, and credit. And rates matter right now: the 30-year fixed averaged 7.03% as of September 24, according to Freddie Mac’s weekly survey, the first time it’s topped 7% since early 2025. On a $300,000 loan, that’s roughly $2,000 a month in principal and interest, about $145 more than at last fall’s rates. Get fully pre-approved, ask your lender to re-run numbers if rates move, and shop at least two or three lenders.

2

Budgeting for the mortgage and nothing else

Your real monthly cost includes property taxes, homeowners insurance (which has climbed sharply in Minnesota after years of hail and wind claims), any HOA dues, and January heating bills that can surprise buyers coming from apartments. One local gotcha: after you close, you need to apply for homestead status with your county to get the lower owner-occupied tax classification. Buy this fall and miss the December 15 deadline, and you could pay more in property taxes next year than you had to.

3

Draining your savings (or skipping help you qualify for)

Putting every last dollar into the down payment leaves nothing for the furnace that quits in February. Many buyers also assume they earn too much for assistance and never check. Minnesota Housing offers first-time and repeat-buyer loan programs with down payment and closing cost help, and the income limits are higher than most people expect. Our buyer resources are a good place to start.

Due Diligence Mistakes That Hit Twin Cities Homes Hardest

Our housing stock has its own personality: 1920s bungalows in South Minneapolis, split-levels in Bloomington, and newer builds out in Maple Grove and Woodbury all come with different risks. Minnesota winters test every one of them.

4

Treating the city’s TISH report like a full inspection

Minneapolis and St. Paul require a Truth-in-Sale of Housing (TISH) evaluation before a home is listed. It’s useful, but it’s a code-focused snapshot, not a deep inspection. Hire your own inspector, and seriously consider two add-ons: a radon test (Minnesota’s geology makes elevated radon common, and sellers must disclose what they know) and a sewer scope for older homes, where tree roots and aging clay pipes can mean a five-figure repair that’s yours once you own it.

5

Buying the snow-covered version of the house

Fall and winter can be great times to buy, but snow hides roofs, yard grading, and drainage problems. Ask the sellers for summer photos, look in the attic for water stains that hint at past ice dams, check the age of the furnace and water heater, and walk the basement for signs of spring moisture. If you’re buying in December, it’s worth asking how the driveway and sidewalks handle a real Minnesota snowfall, too.

Strategy Mistakes in a Shifting 2026 Market

Even well-prepared buyers can stumble on timing and offer strategy, especially when national headlines don’t match what’s happening on their block.

6

Reading the metro instead of the neighborhood

Minneapolis’ median sale price hit about $375,000 in August, up 5.6% from a year earlier, according to Redfin’s Minneapolis market data. But that citywide number hides huge differences. Redfin’s neighborhood data shows homes in Southwest Minneapolis selling in about two weeks, while downtown condos are averaging more than two months. Offering list price might be too low in one spot and too high in another. Check our market insights and community guides for a closer look.

7

Waiting for the “perfect” moment

Some buyers hold out for lower rates, others for spring inventory. Neither is guaranteed. Rates have risen five weeks in a row, and spring brings more listings but also more competition. The better question is whether the monthly payment works for your budget today and whether you plan to stay long enough (typically five years or more) to make buying worthwhile. If both answers are yes, the right house matters more than the calendar.

8

Changing your finances before closing

Financing a new truck, opening a store credit card for furniture, or switching jobs between your accepted offer and closing can derail a loan at the last minute. Lenders often re-check credit and employment right before closing. Keep things boring until the keys are in your hand.

Home Buying Mistakes FAQ: Quick Answers for Twin Cities Buyers

What is the most common mistake first-time buyers make in Minnesota?

Underestimating the total monthly cost. Property taxes, insurance, and winter utilities add a meaningful amount on top of principal and interest, so build your budget around the full payment, not just the loan.

Do I still need a home inspection if the house has a TISH report?

Yes. A Truth-in-Sale of Housing evaluation checks for specific code items, while a private inspection looks at the whole home in far more detail. Many buyers add radon testing and a sewer scope as well.

Is it a mistake to buy a home in the Twin Cities in fall or winter?

Not at all. Off-season buyers often face less competition. Just be extra thorough with inspections, since snow can hide roof, drainage, and grading issues.

The Easiest Mistake to Avoid: Going It Alone

Nearly every one of these home buying mistakes gets easier to dodge with the right agent in your corner: someone who knows which Minneapolis blocks are seeing bidding wars, which inspectors dig deep on 100-year-old foundations, and when to push back on a seller in Eden Prairie versus when to write strong and fast. The trouble is that “a friend of a friend” or the first name on a yard sign isn’t always the right fit.

That’s exactly why MinnMatch exists. We personally match Twin Cities buyers with vetted local agents based on your neighborhood, price range, and priorities, and it’s free for you. See how our matching works, or skip ahead and find your agent match today. Your future self, the one who didn’t make any of these mistakes, will thank you.

August 2026 Twin Cities Real Estate Market: Late Summer Trends, Inventory & What’s Shifting

MinnMatch coffee mug and August 2026 Twin Cities real estate market update notebook overlooking the Minneapolis skyline

Summer isn’t over yet, but the Twin Cities real estate market is already showing the first signs of its late-season shift. Prices are still climbing, but at a more measured pace than the frenzied years of the past decade. Inventory keeps building. And mortgage rates, while still elevated, have settled into a range buyers are starting to plan around rather than wait out. If you’re weighing a move this fall, here’s what the latest numbers say about where things actually stand right now.

Home Prices Are Still Rising — Just Not Like They Used To

The median sales price across the 16-county Twin Cities metro reached $410,000 in June 2026, the most recent full month of closed-sale data available, up 2.1% from a year earlier, according to Minneapolis Area Realtors® (MAAR) data pulled from NorthstarMLS. The average sales price came in at $492,008, up a more modest 0.8% year-over-year — a gap that suggests the priciest segment of the market is cooling faster than the entry- and mid-tier segments that make up most first-time buyer activity. Price per square foot climbed to $223, up 2.0% from last June. None of this points to a market losing steam; it points to one settling into a steadier, more sustainable rhythm after several years of sharper swings.

Inventory Keeps Climbing, and That’s Good News for Buyers

Buyers heading into late summer have more to choose from than they did a year ago. Active inventory stood at 10,897 homes at the end of June, up 5.1% year-over-year, while new listings jumped 10.5% to 7,268 for the month — the strongest new-listing growth of any month so far in 2026. Months of supply ticked up to 2.8, still short of the 5-to-6-month range that typically defines a balanced market, but the highest reading of this year. For buyers who’ve felt boxed out over the past few summers, this is the most breathing room the Twin Cities market has offered in a while.

Mortgage Rates Are Holding in the Mid-6% Range

According to Freddie Mac’s Primary Mortgage Market Survey®, the 30-year fixed rate averaged 6.66% as of July 30, 2026, up slightly from 6.58% the week before but still below the 6.72% mark from a year earlier. The 15-year fixed rate averaged 6.04% over the same period. Rates have moved in a fairly narrow band throughout July — mostly between 6.4% and 6.7% — which has given buyers something they haven’t had in a while: a rate environment stable enough to actually plan around instead of trying to time.

Homes Are Taking a Little Longer to Sell — But Sellers Are Still Winning

The average Twin Cities home took 42 days to sell in June, up 7.7% from 39 days a year ago. That’s a real shift from the sub-three-week pace of peak pandemic-era competition, but it’s still a fast market by any historical measure. Sellers are also still getting close to full asking price: homes sold for 99.6% of original list price on average in June. Closed sales jumped 10.7% year-over-year to 5,602, and pending sales rose 9.7% — both signs that buyer demand hasn’t backed off even as homes take a bit longer to find the right offer.

What This Means as Fall Approaches

Taken together, the data points to a Twin Cities real estate market that’s neither cooling off nor overheating — it’s normalizing. Rising inventory and slightly longer days on market give buyers more leverage than they’ve had in years, while steady price growth and strong percent-of-list-price figures show sellers still have the upper hand in well-priced, well-located homes. As families finish out summer and back-to-school season kicks in, expect the usual late-summer slowdown in showing traffic, followed by a typical uptick in serious, motivated buyers this fall.

Whichever Side of the Table You’re On, Timing Matters

Numbers like these tell you what the market is doing overall, but every Twin Cities suburb and neighborhood is moving at its own pace right now. If you’re trying to figure out what late-summer conditions mean for your specific street, price point, or timeline, MinnMatch can match you with a local agent who knows exactly how your area is trending — no algorithm, just a real person who knows the Twin Cities market inside and out.

July 2026 Twin Cities Real Estate Market Update

MinnMatch July 2026 monthly Twin Cities real estate market update notebook on desk with coffee mug and model home

We’re officially halfway through 2026, and it’s a good time to pause and take stock of the Twin Cities real estate market. The first half of the year didn’t move in a straight line — and June, in particular, threw a few curveballs. New listings climbed, homes sat a little longer, and buyers had more room to negotiate than they’ve had in years. Here’s what actually happened, why it happened, and what it means if you’re planning to buy or sell in the second half of 2026.

Where the Twin Cities Real Estate Market Stands at Mid-Year

Zoom out to the 12 months ending in spring 2026, and the metro-wide picture is one of a market that’s cooled from the frenzy of a few years ago but hasn’t stalled. Twin Cities median sale prices have been running in the high-$300,000s to around $390,000 metro-wide, with single-family homes averaging closer to $429,000, according to Redfin’s Minneapolis market data. That’s modest appreciation — nothing like the double-digit jumps of 2021 and 2022, but still a gain.

Inventory has been the real story of 2026. Active listings have been building for months, which is exactly what a market needs to shift some leverage back toward buyers. Single-family homes are sitting at roughly two months of supply, and townhomes are close behind — both still favor sellers technically, but the gap has narrowed noticeably compared to the tightest years on record.

A Bumpier June — And Why It Happened

If June felt slower than usual, you weren’t imagining it. Local agent Art, who works with buyers and sellers across the metro, summed it up well in his monthly market minute: June was bumpier than usual, with new listings rising, days on market stretching out, and months of supply climbing as a result.

The causes weren’t local — they were macro. Mortgage rates spent much of June anchored in the mid-6% range, with Freddie Mac’s weekly survey showing the 30-year fixed hovering between 6.4% and 6.6% for most of the month. Geopolitical uncertainty overseas pushed oil prices and Treasury yields higher, which dragged mortgage rates along with them, while stubbornly high inflation kept the Federal Reserve on hold rather than cutting rates. Add it up, and buyers had less incentive to move quickly, even with more homes to choose from.

The Golden Handcuffs Are Still the Biggest Obstacle

Beyond the headlines, Art pointed to something a lot of Twin Cities homeowners are quietly wrestling with: the “golden handcuffs” effect. Plenty of people want to move — for more space, a better commute, or a life change — but locked-in mortgage rates from a few years ago are holding them back. Trading a sub-3% rate for something in the mid-6% range can mean a home that’s only 30% more expensive on paper ends up costing nearly double in monthly payment. That math is enough to keep a lot of would-be sellers on the sidelines, which in turn keeps some of the entry-level and move-up inventory buyers want out of reach.

Second Half Outlook: Tools Buyers and Sellers Can Actually Use

The good news, as Art put it, is that uncertainty at the macro level creates opportunity for buyers and sellers willing to act with purpose. A few strategies worth knowing about heading into the second half of 2026:

  • Adjustable-rate mortgages are back in the conversation. For buyers who don’t plan to stay in a home for the full 30 years, an ARM can meaningfully lower the initial rate.
  • Seller-paid rate buydowns are increasingly common. In a market where sellers have more listings to compete against, offering to buy down a buyer’s rate for the first few years is a real concession sellers are making.
  • Negotiating room has genuinely opened up. With months of supply rising, buyers have more standing to ask for repairs, credits, or price adjustments than they did a year or two ago.

None of these tools are one-size-fits-all, and the right move depends heavily on your timeline, your down payment, and your local submarket — which is exactly where having someone who watches these numbers every week pays off.

Whether you’re trying to time a move around today’s rates or figure out if now’s the right moment to finally sell, the details matter more in a market like this one. MinnMatch can match you with a local agent who knows exactly what’s happening in your neighborhood — not just the metro averages. Curious how the process works? See how MinnMatch works.