
The Most Common Home Buying Mistakes in the Twin Cities in 2026 — And How to Avoid Them

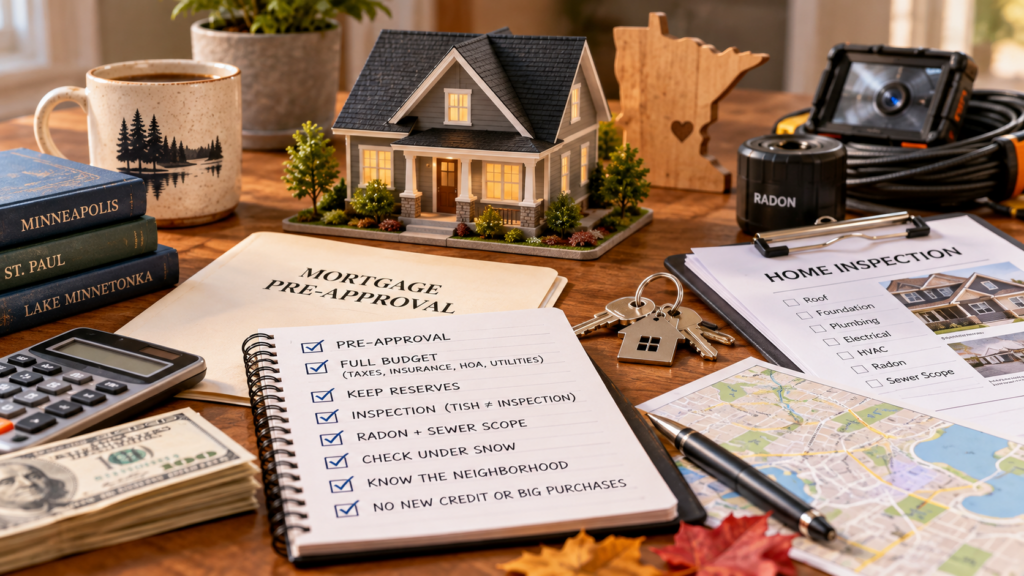
Home buying checklist for Twin Cities buyers with mortgage pre-approval, inspection form, radon test, keys, and Minnesota map

Buying a home in the Twin Cities is one of the biggest financial moves most of us will ever make, and in 2026 the margin for error is thinner than it’s been in years. Mortgage rates just crossed 7%, prices keep inching up, and the metro’s neighborhoods are moving at wildly different speeds. The good news? Most home buying mistakes are completely avoidable once you know where people tend to trip up. Here are the eight we see most often across Minneapolis, St. Paul, and the suburbs, plus exactly how to sidestep each one.

Money Mistakes: The Home Buying Mistakes That Start Before Your First Showing

The costliest errors usually happen at the kitchen table, long before you walk into an open house in Plymouth or Highland Park. Get the numbers right first and every decision after gets easier.

1

Shopping before you have a real pre-approval

An online “pre-qualification” isn’t the same as a lender actually reviewing your income, assets, and credit. And rates matter right now: the 30-year fixed averaged 7.03% as of September 24, according to Freddie Mac’s weekly survey, the first time it’s topped 7% since early 2025. On a $300,000 loan, that’s roughly $2,000 a month in principal and interest, about $145 more than at last fall’s rates. Get fully pre-approved, ask your lender to re-run numbers if rates move, and shop at least two or three lenders.

2

Budgeting for the mortgage and nothing else

Your real monthly cost includes property taxes, homeowners insurance (which has climbed sharply in Minnesota after years of hail and wind claims), any HOA dues, and January heating bills that can surprise buyers coming from apartments. One local gotcha: after you close, you need to apply for homestead status with your county to get the lower owner-occupied tax classification. Buy this fall and miss the December 15 deadline, and you could pay more in property taxes next year than you had to.

3

Draining your savings (or skipping help you qualify for)

Putting every last dollar into the down payment leaves nothing for the furnace that quits in February. Many buyers also assume they earn too much for assistance and never check. Minnesota Housing offers first-time and repeat-buyer loan programs with down payment and closing cost help, and the income limits are higher than most people expect. Our buyer resources are a good place to start.

Due Diligence Mistakes That Hit Twin Cities Homes Hardest

Our housing stock has its own personality: 1920s bungalows in South Minneapolis, split-levels in Bloomington, and newer builds out in Maple Grove and Woodbury all come with different risks. Minnesota winters test every one of them.

4

Treating the city’s TISH report like a full inspection

Minneapolis and St. Paul require a Truth-in-Sale of Housing (TISH) evaluation before a home is listed. It’s useful, but it’s a code-focused snapshot, not a deep inspection. Hire your own inspector, and seriously consider two add-ons: a radon test (Minnesota’s geology makes elevated radon common, and sellers must disclose what they know) and a sewer scope for older homes, where tree roots and aging clay pipes can mean a five-figure repair that’s yours once you own it.

5

Buying the snow-covered version of the house

Fall and winter can be great times to buy, but snow hides roofs, yard grading, and drainage problems. Ask the sellers for summer photos, look in the attic for water stains that hint at past ice dams, check the age of the furnace and water heater, and walk the basement for signs of spring moisture. If you’re buying in December, it’s worth asking how the driveway and sidewalks handle a real Minnesota snowfall, too.

Strategy Mistakes in a Shifting 2026 Market

Even well-prepared buyers can stumble on timing and offer strategy, especially when national headlines don’t match what’s happening on their block.

6

Reading the metro instead of the neighborhood

Minneapolis’ median sale price hit about $375,000 in August, up 5.6% from a year earlier, according to Redfin’s Minneapolis market data. But that citywide number hides huge differences. Redfin’s neighborhood data shows homes in Southwest Minneapolis selling in about two weeks, while downtown condos are averaging more than two months. Offering list price might be too low in one spot and too high in another. Check our market insights and community guides for a closer look.

7

Waiting for the “perfect” moment

Some buyers hold out for lower rates, others for spring inventory. Neither is guaranteed. Rates have risen five weeks in a row, and spring brings more listings but also more competition. The better question is whether the monthly payment works for your budget today and whether you plan to stay long enough (typically five years or more) to make buying worthwhile. If both answers are yes, the right house matters more than the calendar.

8

Changing your finances before closing

Financing a new truck, opening a store credit card for furniture, or switching jobs between your accepted offer and closing can derail a loan at the last minute. Lenders often re-check credit and employment right before closing. Keep things boring until the keys are in your hand.

Home Buying Mistakes FAQ: Quick Answers for Twin Cities Buyers

What is the most common mistake first-time buyers make in Minnesota?

Underestimating the total monthly cost. Property taxes, insurance, and winter utilities add a meaningful amount on top of principal and interest, so build your budget around the full payment, not just the loan.

Do I still need a home inspection if the house has a TISH report?

Yes. A Truth-in-Sale of Housing evaluation checks for specific code items, while a private inspection looks at the whole home in far more detail. Many buyers add radon testing and a sewer scope as well.

Is it a mistake to buy a home in the Twin Cities in fall or winter?

Not at all. Off-season buyers often face less competition. Just be extra thorough with inspections, since snow can hide roof, drainage, and grading issues.

The Easiest Mistake to Avoid: Going It Alone

Nearly every one of these home buying mistakes gets easier to dodge with the right agent in your corner: someone who knows which Minneapolis blocks are seeing bidding wars, which inspectors dig deep on 100-year-old foundations, and when to push back on a seller in Eden Prairie versus when to write strong and fast. The trouble is that “a friend of a friend” or the first name on a yard sign isn’t always the right fit.

That’s exactly why MinnMatch exists. We personally match Twin Cities buyers with vetted local agents based on your neighborhood, price range, and priorities, and it’s free for you. See how our matching works, or skip ahead and find your agent match today. Your future self, the one who didn’t make any of these mistakes, will thank you.
Bidding Wars in the Twin Cities in 2026: How to Win Without Overpaying

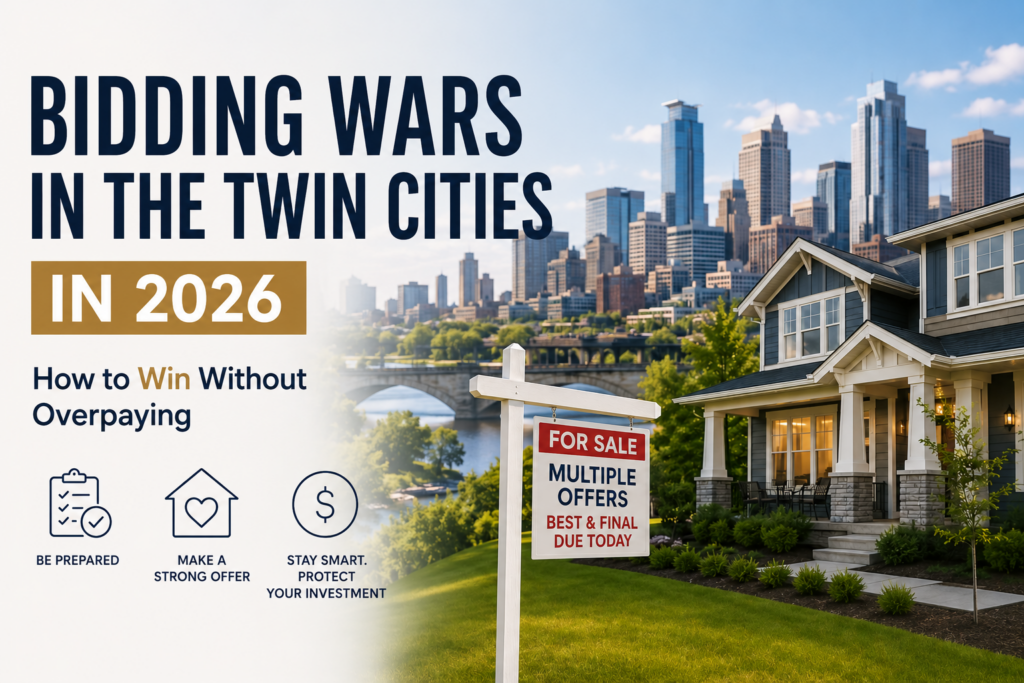
Twin Cities home with "Multiple Offers – Best & Final Due Today" sign in front yard, Minneapolis skyline in background

If you’ve been house hunting in the Twin Cities this summer, you already know the feeling: you find the right house, fall in love with it — and then find out three other buyers have too. Bidding wars are a real part of the Twin Cities housing market in 2026, even as conditions have shifted compared to the frenzy of a few years ago. The good news? Winning a competitive offer situation doesn’t have to mean throwing caution to the wind. With the right strategy, you can stand out from the competition and protect yourself from overpaying.

What’s Driving Competition in the Twin Cities Right Now

The Twin Cities market in 2026 is more nuanced than it was in 2021 or 2022, but that doesn’t mean it’s easy out there for buyers. Inventory has improved — new listings were up nearly 9% across Minnesota earlier this year — but well-priced, move-in-ready homes in desirable suburbs like Eden Prairie, Plymouth, and Edina still routinely draw multiple offers.

According to data from Redfin, roughly 31% of Minnesota homes sold above list price in April 2026. That’s down slightly from a year ago — but it still means nearly one in three sales is competitive. And in the most in-demand ZIP codes across the metro, that number is higher.

What’s changed is where the competition is concentrated. Homes that are well-priced and well-prepared still generate strong interest fast. Overpriced listings, or homes that need significant work, are sitting longer. That means buyers who target the right homes in the right condition need to come in ready — because those are exactly the homes drawing multiple offers.

Step One: Get Your Financing Locked Down Before You Need It

In a competitive offer situation, a basic pre-approval letter is the bare minimum. If you’re serious about winning in a bidding war in the Twin Cities, consider going further and getting fully underwritten before you make an offer. Some lenders now offer “verified approval” or “credit-approved” status — meaning your income, assets, and credit have all been reviewed in advance. To a seller, that’s nearly as reassuring as a cash offer.

Local lenders often carry weight here too. A seller and their agent are more likely to be confident in an offer backed by a lender they recognize and have worked with. Ask your buyer’s agent for recommendations — they’ll know which local lenders close cleanly and on time.

How to Structure a Competitive Offer Without Blowing Your Budget

Once you’re pre-approved, the offer itself is where strategy really matters. Here are the tools experienced Twin Cities buyers and their agents use to compete effectively:

Escalation clauses. An escalation clause tells the seller: “I’ll pay $X, but I’m willing to automatically increase my offer by $Y increments above any competing offer, up to a maximum of $Z.” For example, you might offer $415,000 with an escalation clause up to $435,000 in $2,500 increments. This keeps you competitive without leading with your ceiling — but be sure to require proof of any competing offer that triggers the escalation. Your agent can build this into the purchase agreement.

Increased earnest money. Standard earnest money in Minnesota is typically 1–2% of the purchase price. In a competitive situation, bumping that to 3–5% signals serious commitment. It tells the seller: this buyer isn’t going to walk away over small stuff. Just know that earnest money is at risk if you back out for non-contingency reasons.

Appraisal gap coverage. When you offer above list price, there’s always a risk the home appraises for less than what you offered. Lenders will only finance up to the appraised value — meaning if you offered $430,000 and it appraises at $415,000, you need to cover that $15,000 gap out of pocket or renegotiate. Agreeing in writing to cover an appraisal gap up to a specific amount can be the difference between winning and losing in a multiple-offer situation.

Seller-friendly terms. Price isn’t everything. Flexibility on closing date — whether the seller needs a quick close or extra time to find their next home — can make your offer more attractive even if it’s not the highest number. Ask your agent what the seller’s situation is before structuring your offer.

Non-round offer numbers. It sounds small, but offers like $412,500 stand out from a pile of round numbers. The logic: it suggests the buyer has done careful analysis rather than just guessing.

What About Contingencies? Know What’s Safe to Modify

One of the biggest questions buyers face in a bidding war is which contingencies to keep and which to modify. The short answer: never fully waive the inspection contingency unless you truly know what you’re walking into. A better approach is to shorten the inspection window to 5–7 days, or add an “informational only” clause — meaning you’ll get an inspection but commit to not requesting repairs for minor cosmetic issues. That shows the seller you’re reasonable without leaving yourself exposed to major unknowns.

The financing contingency protects you if your loan falls through, and in most cases, you want to keep it — especially if you’re not waiving the appraisal contingency too. That said, a fully underwritten pre-approval (as mentioned above) can give sellers more confidence in your financing even with the contingency intact.

The Agent Advantage: Why Your Representation Matters Most in a Bidding War

In a competitive offer situation, your agent isn’t just submitting paperwork — they’re your strategist, your relationship builder with the listing agent, and your real-time advisor when things move fast. The best Twin Cities buyer’s agents know how to read a listing agent’s cues, ask the right questions about what the seller actually needs, and structure an offer that addresses those needs beyond just price.

Speed matters too. In a multiple-offer situation, getting your offer in promptly — with a clean, complete package — can matter as much as the numbers themselves. An experienced agent who handles competitive markets regularly will have these systems down.

For additional data on how the broader Minnesota market is performing, Minneapolis Area Realtors publishes regular market reports that are worth reviewing with your agent before you write an offer.

Don’t Chase — Protect Yourself from Overbidding

Bidding wars create real psychological pressure, and it’s easy to let emotion drive you past a number that actually makes sense for your budget and the market. A few guardrails to keep in mind:

Set your cap before the offer, not during it. Decide your absolute maximum price before you’re in the heat of a bidding situation. Write it down. Your agent can help you use comparable sales to anchor that number in real market data — not emotion.

Understand the appraisal risk before offering above list. If you’re offering significantly above asking, make sure you know roughly what comparable homes have sold for nearby. If you’re covered by cash reserves for a gap, fine — if not, know your risk.

Sometimes the right move is to let it go. In 2026’s Twin Cities market, the right home at the right price will come along. Overpaying under pressure is a decision that follows you for years. Your agent should be your voice of reason, not just your advocate.

Look at homes that have been sitting. Not every opportunity is a bidding war. Homes that have been on the market for 3–4 weeks or longer — especially those with cosmetic issues or awkward floor plans — often have motivated sellers and little competition. Your agent can help you identify these and evaluate whether they’re worth pursuing.

Ready to compete — and win — in the Twin Cities market?

The difference between winning a bidding war and losing one often comes down to the agent in your corner. MinnMatch connects Twin Cities buyers with experienced, vetted local agents who know how to write offers that win — without putting you at financial risk. The service is completely free for buyers.

Find Your Agent — It’s Free