Buying a Home with a Well and Septic System in Minnesota

Well water samples, a water test kit and a site plan showing a home’s well and septic drainfield, with a Minnesota lake and fall trees in the background.

Head a few miles past the last sewer line in the Twin Cities metro — the wooded lots outside Prior Lake, the horse country around Independence and Medina, the acreage near Lake Elmo and Afton — and you’ll start seeing listings that say “private well” and “septic” in the details. Buying a home with well and septic in Minnesota is very doable, and plenty of people love the space and privacy that come with it. But it adds a few steps most city buyers never think about: a state well disclosure, water testing, and a septic inspection that may or may not be required depending on which county you’re buying in. Here’s what to know before you write an offer.

What Minnesota Requires When You Buy a Home with Well and Septic

Minnesota puts the disclosure burden on the seller for both systems. On the well side, the seller must give you a written well disclosure before you sign a purchase agreement. According to the Minnesota Department of Health’s well disclosure guidance, that statement includes a map of every well on the property and whether each one is in use, not in use, or sealed. At closing, a Well Disclosure Certificate is filed with the deed, along with a $54 fee that the buyer provides.

Pay close attention to that “not in use” box. If an old, unused well isn’t sealed, returned to service, or covered by a maintenance permit before closing, that responsibility passes to you. Many lenders want unused wells sealed by a licensed contractor, so it’s worth negotiating who handles it up front.

Septic works similarly. Sellers must disclose in writing how sewage is handled, where the system (and any abandoned system) is located, and whether — to their knowledge — it complies with state rules. The Minnesota Pollution Control Agency is clear, though, that a disclosure is not an inspection. It’s the seller’s best knowledge, not a professional evaluation.

Septic Compliance Inspections: It Depends on the County

This is where a lot of buyers get tripped up. Minnesota doesn’t require a septic compliance inspection at sale statewide — but many counties, cities, and townships do, especially in shoreland areas. The difference across the metro is real:

  • Washington County requires a compliance inspection when a property with septic is sold, unless a recent inspection or new-system certificate is already on file.
  • Scott County (home to the rural areas around Prior Lake) does not require one at sale — though the county notes many buyers order one anyway, and lenders sometimes require it.
  • Other counties and cities each set their own rules, so the answer for a hobby farm in Corcoran may differ from a lake lot in Chisago County.

Our advice: if you’re buying a home with well and septic, even where an inspection isn’t required, make your offer contingent on a compliance inspection by an MPCA-licensed inspector. A certificate of compliance is generally good for three years on an existing system and five years on a new one. If a system is found failing, local rules set the repair timeline, and an imminent threat to public health typically has to be fixed within months — not years.

One timely note for fall and winter buyers: frozen ground can complicate a septic evaluation. If you’re shopping between now and spring, ask early how the local county handles winter inspections so it doesn’t stall your closing.

Testing the Well Water Before You Close

Minnesota doesn’t require a water test at sale, and a standard home inspection usually doesn’t cover the well. That makes this step entirely up to you — and it’s one you shouldn’t skip. The Minnesota Department of Health recommends that private well owners test for:

  • Coliform bacteria — every year
  • Nitrate — every year
  • Arsenic, lead, and manganese — at least once

Arsenic and manganese occur naturally in groundwater across parts of Minnesota, so a one-time test during your purchase is the perfect moment to check. Use an accredited lab, and ask the seller for past test results, well construction records, and details on any water softener or treatment system. Your agent can also look the well up in the Minnesota Well Index — though wells drilled before 1974 often have no public record at all.

Budgeting for Life with a Private Well and Septic System

The trade-off for rural living is that you’re your own utility. You won’t get a city water and sewer bill, but you’ll take on maintenance that city homeowners never see:

  • Septic pumping every two to three years, plus periodic inspections.
  • Annual water testing for bacteria and nitrate.
  • Well pump and pressure tank repairs or replacement over time.
  • A septic replacement fund. A failed system — especially one that needs a mound because of soil or groundwater conditions — can run well into five figures.

If an inspection turns up a failing system, that’s not automatically a deal-breaker. It’s a negotiation point: a price reduction, a seller-paid replacement, or an escrow holdback can all work. This is exactly where an agent who’s closed rural deals before earns their keep.

FAQ: Buying a Home with Well and Septic in Minnesota

Is a septic inspection required to sell a house in Minnesota?

Not statewide. Requirements are set locally — Washington County requires one at sale, for example, while Scott County does not. Lenders may require one either way, and buyers can always make their offer contingent on one.

Does a home inspection cover the well and septic?

Usually not in any depth. Plan on a separate septic compliance inspection by an MPCA-licensed inspector and a water test through an accredited lab. A licensed well contractor can evaluate the well itself if there are concerns.

Who pays to seal an unused well?

It’s negotiable. If the seller doesn’t address an unused well before closing, the responsibility transfers to the buyer, so settle it in the purchase agreement.

Find an Agent Who Knows Rural Twin Cities Properties

A home with well and septic can give you the room, quiet, and land that’s hard to find closer in — as long as you go in with the right inspections, contingencies, and expectations. Not every agent has walked a buyer through a septic compliance report or a well disclosure certificate, and that experience matters. MinnMatch personally connects buyers with vetted local agents who know the exurban edges of the metro, from Scott County to the St. Croix Valley. See how our matching works, or get matched with an agent who’s done this before — it’s free for buyers. For more first-step guidance, visit our buyer resources.
What Makes a Great Real Estate Agent in 2026? 8 Traits the Best Twin Cities Agents Share

Fall home listing portfolio, keys, and coffee on a lakeside desk — prep work of a great real estate agent in the Twin Cities

Ask ten Twin Cities homeowners what makes a great real estate agent and you’ll get ten different answers — “they answered my texts,” “they knew the neighborhood cold,” “they talked me out of a house with a wet basement.” All of those are right, and none of them is the whole picture. In 2026, with new rules around buyer agreements and a metro market that’s quick but no longer frantic, the gap between an okay agent and a great one shows up in real dollars and real stress. Here are the eight traits the best Twin Cities agents share, plus how to spot them before you sign anything.

Why a Great Real Estate Agent Matters More in 2026

Two things changed the stakes. First, since August 2024, buyers working with an MLS-participating agent sign a written buyer agreement before touring homes — meaning you’re committing to an agent, and to how they’ll be paid, earlier than buyers used to. Commissions are spelled out and negotiable, so knowing what a great real estate agent actually delivers for that fee matters more than ever.

Second, the market itself demands more judgment. According to Redfin’s Minneapolis housing market data, homes sold in a median of 23 days in August 2026, and about 41.5% went for more than asking — down roughly four points from a year earlier. That’s a market where some homes still draw multiple offers and others sit. Telling the difference, on the right house, at the right moment, is exactly what you’re hiring an agent to do. For a broader read on metro trends, the Minneapolis Area REALTORS® publish regular market reports, and you can find our local takes in MinnMatch Market Insights.

8 Traits Every Great Real Estate Agent Shares

Plenty of agents are friendly, licensed, and hardworking. These are the traits that separate the ones you’ll recommend to your sister.

1

Local knowledge that goes past the ZIP code

A great agent knows that Minneapolis and Saint Paul require a Truth-in-Sale-of-Housing evaluation before a home is listed, that parts of Plymouth feed into four different school districts, and what to ask about docks and shoreline on Lake Minnetonka. That block-by-block fluency is hard to fake. Browse our Twin Cities community guides to see how much varies from one suburb to the next.

2

Pricing discipline, not pricing flattery

The agent who quotes sellers the highest number isn’t doing them a favor — an overpriced listing goes stale and usually sells for less in the end. On the buying side, a great agent tells you when a bidding war is worth joining and when you’re about to overpay for a house that’ll be available next week. Either way, they show you the comps and explain their reasoning.

3

Communication that fits how you work

Some clients want a text after every showing; others want a Friday summary. The best agents ask which you prefer, set expectations up front, and — this is the big one — deliver bad news fast. A heads-up about a low appraisal on Tuesday beats a surprise at the closing table.

4

Negotiation skill beyond the price tag

Price is only one lever. Inspection repairs, seller credits, rate buydowns, closing dates, and a few weeks of rent-back for a seller who hasn’t found their next place can all be worth thousands. A great agent knows which terms matter most to the other side and trades accordingly — calmly, and without burning the relationship mid-deal.

5

A trusted local bench

Lenders who close on time, inspectors who test for radon and scope the sewer line, title companies that catch problems early, and contractors who’ll actually return a call in March. A well-connected agent turns a two-week scramble into a few phone calls.

6

Four-season Minnesota savvy

Buying in January means a roof hidden under snow, an air conditioner that can’t be safely tested in the cold, and ice dams that may only show up as a stain on the ceiling. Selling in May means competing with the spring rush. A great Minnesota agent plans around the calendar instead of pretending it doesn’t exist.

7

Honesty about fit — including their own

The best agents will tell you a house isn’t right for you, even when you love the kitchen. They’ll also tell you when they aren’t the right fit — a downtown condo specialist who refers a lakeshore buyer to someone who lives and breathes Lake Minnetonka is doing that buyer a real service.

8

Transparency about contracts and cost

A great agent walks you through the buyer agreement or listing contract line by line: how long it lasts, how they’re paid, and what you get for that fee. If they rush you past the paperwork, take note. It’s also worth confirming their license is active through the Minnesota Department of Commerce license lookup — it takes about a minute.

How to Spot a Great Real Estate Agent Before You Sign

Every agent will tell you they’re responsive, local, and a strong negotiator. The trick is looking for evidence instead of claims. Ask about recent deals in your specific area, not their career totals. Ask them to describe a transaction that nearly fell apart and what they did about it — great agents have good stories here, and they tell them without blaming everyone else. And pay attention to the first conversation itself: did they ask about your goals, or launch straight into a pitch?

If you want a ready-made list of questions, our articles library includes full agent interview guides for both buyers and sellers.

Frequently Asked Questions

Is the agent with the most sales always the best choice?

Not necessarily. High volume shows experience, but it can also mean you’ll spend more time with an assistant than with the agent. A great real estate agent for you is one with solid recent experience in your area and price range — and the bandwidth to give your move real attention.

How quickly should a good agent respond?

Same business day is a reasonable baseline, and much faster when an offer is in play. More important than speed is consistency: you shouldn’t have to wonder whether your message landed.

Does it cost anything to get matched with an agent through MinnMatch?

No. MinnMatch is free for buyers and sellers. We introduce you to vetted local agents, and you decide who to work with — no obligation.

Skip the Guesswork and Get Matched

Vetting agents for all eight of these traits takes time most people don’t have in the middle of a move. That’s the work we do every day. MinnMatch is a human-powered matchmaking service — think of us as a recruiter for real estate — that pairs Twin Cities buyers and sellers with handpicked local agents who know your neighborhood and fit the way you like to work.

Curious how it works? Take a look at our matching process, or when you’re ready, tell us a little about your move and we’ll introduce you to a great real estate agent who fits — free, with no obligation.

Should You Buy a Home in the Twin Cities Before Year-End 2026? Here’s What to Consider

Snow-dusted model house, keys, and a December 2026 calendar on a wooden table, representing a year-end home purchase

Every fall, the same question starts popping up around Twin Cities kitchen tables: should we buy a home before year-end, or wait for spring? In 2026, that question has a few new wrinkles. Mortgage rates just climbed to their highest level in nearly three years, inventory is up, and a lot of buyers have quietly stepped back. That combination cuts both ways. For some households it’s a genuine opening; for others, waiting really is the smarter move. Here’s an honest look at both sides so you can decide what makes sense for you.

Twin Cities Market Snapshot · Fall 2026

11,970

Homes for sale, up 9.1% from a year ago

–15.9%

Weekly pending sales vs. the same week last year

7.28%

Average 30-year fixed rate (Oct. 1, 2026)

$395,000

12-month median sales price, up 1.5%

Sources: Minneapolis Area REALTORS®/NorthstarMLS (inventory and pending sales for the week ending Sept. 12, 2026; median price for Sept. 2025–Aug. 2026); Freddie Mac Primary Mortgage Market Survey.

Where the Twin Cities Market Stands Heading Into Q4

The biggest story this fall is rates. According to Freddie Mac’s weekly survey, the average 30-year fixed rate hit 7.28% on October 1, up from 6.71% just four weeks earlier and the highest reading since late 2023. On a $395,000 home with 10% down, that jump alone adds roughly $135 a month to principal and interest.

Buyers have noticed. Minneapolis Area REALTORS® reports that showing activity was down 12.6% year over year in late September, with the busiest price band ($300K–$400K) down more than 16%. Meanwhile, sellers keep listing. More homes and fewer shoppers is the textbook recipe for buyer leverage, and that’s exactly what’s happening across much of the metro. Homes are also taking a bit longer to sell. Redfin’s Minneapolis data shows homes selling in about 20 days on average, compared to 18 a year ago.

Prices, though, haven’t cracked. The metro median is still up modestly year over year, and well-priced homes in popular suburbs like Plymouth and Edina still move quickly. So this isn’t a fire sale. It’s a market where patient, prepared buyers have more room to negotiate than they’ve had in years. For deeper monthly numbers, our market insights page tracks the trends as they come in.

5 Reasons to Buy a Home Before Year-End

If your finances are solid and you’ve been planning to move anyway, the next 90 days have some real advantages.

1

You’ll have more negotiating power

With pending sales down and inventory up, many sellers are open to price reductions, inspection repairs, or covering closing costs. Those conversations were hard to have in a bidding war.

2

Seller credits can soften high rates

Instead of a lower price, some buyers ask for a seller-paid rate buydown. Depending on the structure, that can trim your monthly payment more than a price cut of the same size. Your lender can run the numbers both ways.

3

Fall and winter sellers tend to be motivated

People listing in October through December usually have a reason: a job relocation, a new home already purchased, a life change. Motivated sellers are often more flexible on terms and timing.

4

You’ll beat the spring crowd

Twin Cities buyer activity reliably picks back up in March and April. If rates ease at all over the winter, the buyers who sat out this fall will come back at once, and competition will return with them.

5

You can refinance later, but you can’t renegotiate the price

If rates fall in 2027, a refinance could lower your payment. The price and concessions you negotiate now are locked in for good. That said, never buy counting on a refinance. Make sure today’s payment works on its own.

When Waiting Until Spring 2027 Makes More Sense

Urgency isn’t a reason by itself, and not everyone should buy a home before year-end. Holding off is often the right call if any of these sound like you:

The payment at 7%+ would stretch you thin. If the monthly number only works with zero cushion for a furnace repair or a January heating bill, give yourself more time to save or pay down debt. Minnesota winters have a way of finding the weak spots in a budget.

Your job or income is in flux. A new role, an upcoming raise, or a pending move can all change what you qualify for. It’s usually wise to let that settle first.

You need a specific home type that’s scarce right now. Lakefront properties, homes in a particular school district, or one-level living in a specific suburb can have thin selection in late fall. Spring brings more listings, even if it also brings more competition.

You’re not sure where you want to live yet. Use the winter to tour neighborhoods, compare commutes, and explore our community guides. Buying the right home a few months later beats buying the wrong one in December.

A Quick Gut-Check Before You Decide

Before you commit to a timeline, sit down with these questions. If you can answer yes to most of them, a year-end purchase is probably worth pursuing:

  • Do I have a current mortgage pre-approval at today’s rates, not last summer’s?
  • Is the monthly payment comfortable, with room left for savings and surprises?
  • Do I plan to stay at least five years, so price swings and closing costs even out?
  • Can I handle a move during the holidays or the first stretch of winter?
  • Do I know which neighborhoods and price range actually fit my life?

If a few of those are still question marks, that’s fine. It just means your timeline is spring, and you can use the next few months to get ready. Our buyer resources are a good place to start.

FAQ: Buying a Home Before Year-End in the Twin Cities

Is it too late to close on a home by December 31, 2026?

Not yet. Most financed purchases take 30 to 45 days from accepted offer to closing. If closing in 2026 matters to you, aim to have an accepted offer by mid-November. That leaves breathing room for appraisals, inspections, and holiday-season scheduling delays at lenders and title companies.

Should I wait for mortgage rates to come down before buying?

Nobody can reliably predict rates, and they’ve moved sharply in both directions this year. Waiting for lower rates can mean facing more competition and firmer prices in spring. The better question is whether the payment works for you today. If it does, and you find the right home, timing the rate market matters less than you’d think.

Are there tax advantages to closing before year-end?

Possibly. Some buyers can deduct prepaid mortgage interest, points, and property taxes paid at a December closing on their 2026 return, but it depends on whether you itemize. Talk with a tax professional before letting taxes drive your timeline.

The Right Timing Starts With the Right Agent

Whether you decide to buy a home before year-end or plan for a spring 2027 move, the decision gets easier with someone in your corner who knows your target neighborhoods block by block. A good local agent can tell you which sellers are negotiating, where concessions are on the table, and whether a home is priced right for today’s market, not last spring’s.

That’s what MinnMatch is here for. We personally match Twin Cities buyers with vetted local agents who fit their goals, timeline, and communication style. It’s free, there’s no pressure, and you’re never handed off to an algorithm. See how it works, or find your agent match today and start the conversation on your terms.

The Most Common Home Buying Mistakes in the Twin Cities in 2026 — And How to Avoid Them

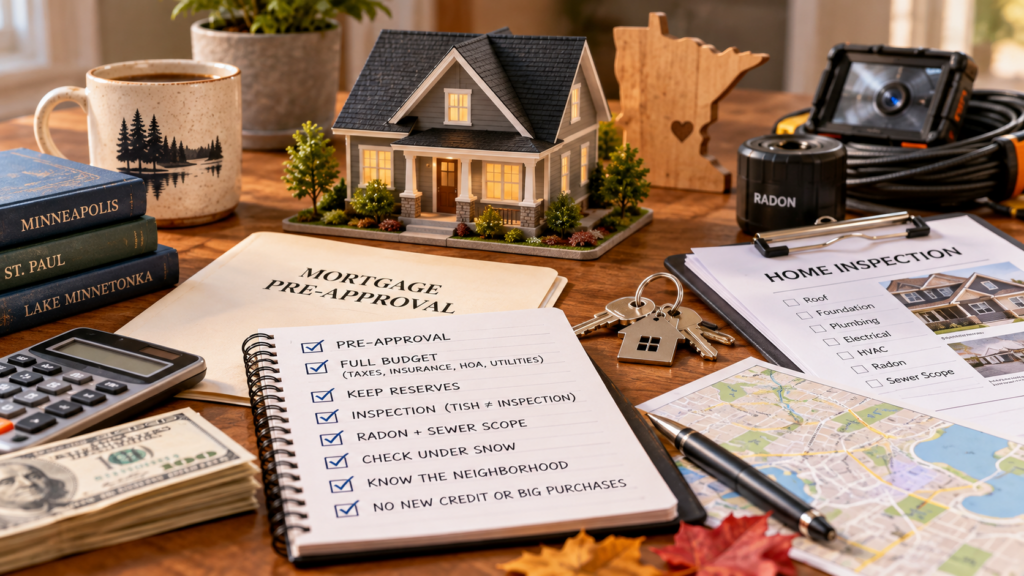
Home buying checklist for Twin Cities buyers with mortgage pre-approval, inspection form, radon test, keys, and Minnesota map

Buying a home in the Twin Cities is one of the biggest financial moves most of us will ever make, and in 2026 the margin for error is thinner than it’s been in years. Mortgage rates just crossed 7%, prices keep inching up, and the metro’s neighborhoods are moving at wildly different speeds. The good news? Most home buying mistakes are completely avoidable once you know where people tend to trip up. Here are the eight we see most often across Minneapolis, St. Paul, and the suburbs, plus exactly how to sidestep each one.

Money Mistakes: The Home Buying Mistakes That Start Before Your First Showing

The costliest errors usually happen at the kitchen table, long before you walk into an open house in Plymouth or Highland Park. Get the numbers right first and every decision after gets easier.

1

Shopping before you have a real pre-approval

An online “pre-qualification” isn’t the same as a lender actually reviewing your income, assets, and credit. And rates matter right now: the 30-year fixed averaged 7.03% as of September 24, according to Freddie Mac’s weekly survey, the first time it’s topped 7% since early 2025. On a $300,000 loan, that’s roughly $2,000 a month in principal and interest, about $145 more than at last fall’s rates. Get fully pre-approved, ask your lender to re-run numbers if rates move, and shop at least two or three lenders.

2

Budgeting for the mortgage and nothing else

Your real monthly cost includes property taxes, homeowners insurance (which has climbed sharply in Minnesota after years of hail and wind claims), any HOA dues, and January heating bills that can surprise buyers coming from apartments. One local gotcha: after you close, you need to apply for homestead status with your county to get the lower owner-occupied tax classification. Buy this fall and miss the December 15 deadline, and you could pay more in property taxes next year than you had to.

3

Draining your savings (or skipping help you qualify for)

Putting every last dollar into the down payment leaves nothing for the furnace that quits in February. Many buyers also assume they earn too much for assistance and never check. Minnesota Housing offers first-time and repeat-buyer loan programs with down payment and closing cost help, and the income limits are higher than most people expect. Our buyer resources are a good place to start.

Due Diligence Mistakes That Hit Twin Cities Homes Hardest

Our housing stock has its own personality: 1920s bungalows in South Minneapolis, split-levels in Bloomington, and newer builds out in Maple Grove and Woodbury all come with different risks. Minnesota winters test every one of them.

4

Treating the city’s TISH report like a full inspection

Minneapolis and St. Paul require a Truth-in-Sale of Housing (TISH) evaluation before a home is listed. It’s useful, but it’s a code-focused snapshot, not a deep inspection. Hire your own inspector, and seriously consider two add-ons: a radon test (Minnesota’s geology makes elevated radon common, and sellers must disclose what they know) and a sewer scope for older homes, where tree roots and aging clay pipes can mean a five-figure repair that’s yours once you own it.

5

Buying the snow-covered version of the house

Fall and winter can be great times to buy, but snow hides roofs, yard grading, and drainage problems. Ask the sellers for summer photos, look in the attic for water stains that hint at past ice dams, check the age of the furnace and water heater, and walk the basement for signs of spring moisture. If you’re buying in December, it’s worth asking how the driveway and sidewalks handle a real Minnesota snowfall, too.

Strategy Mistakes in a Shifting 2026 Market

Even well-prepared buyers can stumble on timing and offer strategy, especially when national headlines don’t match what’s happening on their block.

6

Reading the metro instead of the neighborhood

Minneapolis’ median sale price hit about $375,000 in August, up 5.6% from a year earlier, according to Redfin’s Minneapolis market data. But that citywide number hides huge differences. Redfin’s neighborhood data shows homes in Southwest Minneapolis selling in about two weeks, while downtown condos are averaging more than two months. Offering list price might be too low in one spot and too high in another. Check our market insights and community guides for a closer look.

7

Waiting for the “perfect” moment

Some buyers hold out for lower rates, others for spring inventory. Neither is guaranteed. Rates have risen five weeks in a row, and spring brings more listings but also more competition. The better question is whether the monthly payment works for your budget today and whether you plan to stay long enough (typically five years or more) to make buying worthwhile. If both answers are yes, the right house matters more than the calendar.

8

Changing your finances before closing

Financing a new truck, opening a store credit card for furniture, or switching jobs between your accepted offer and closing can derail a loan at the last minute. Lenders often re-check credit and employment right before closing. Keep things boring until the keys are in your hand.

Home Buying Mistakes FAQ: Quick Answers for Twin Cities Buyers

What is the most common mistake first-time buyers make in Minnesota?

Underestimating the total monthly cost. Property taxes, insurance, and winter utilities add a meaningful amount on top of principal and interest, so build your budget around the full payment, not just the loan.

Do I still need a home inspection if the house has a TISH report?

Yes. A Truth-in-Sale of Housing evaluation checks for specific code items, while a private inspection looks at the whole home in far more detail. Many buyers add radon testing and a sewer scope as well.

Is it a mistake to buy a home in the Twin Cities in fall or winter?

Not at all. Off-season buyers often face less competition. Just be extra thorough with inspections, since snow can hide roof, drainage, and grading issues.

The Easiest Mistake to Avoid: Going It Alone

Nearly every one of these home buying mistakes gets easier to dodge with the right agent in your corner: someone who knows which Minneapolis blocks are seeing bidding wars, which inspectors dig deep on 100-year-old foundations, and when to push back on a seller in Eden Prairie versus when to write strong and fast. The trouble is that “a friend of a friend” or the first name on a yard sign isn’t always the right fit.

That’s exactly why MinnMatch exists. We personally match Twin Cities buyers with vetted local agents based on your neighborhood, price range, and priorities, and it’s free for you. See how our matching works, or skip ahead and find your agent match today. Your future self, the one who didn’t make any of these mistakes, will thank you.

Fall Home Buying in the Twin Cities in 2026: Less Competition, More Motivated Sellers

Twin Cities neighborhood in fall with autumn foliage and downtown Minneapolis skyline in the background

If you spent the spring and summer getting outbid, ghosted by sellers, or priced out of your favorite Twin Cities neighborhood, take a breath — the season is changing, and so is your leverage. Fall home buying in the Twin Cities has quietly become one of the smarter plays in this market: fewer buyers are actively looking, showings slow down, and the sellers still listing in October and November tend to have real reasons to get a deal done before winter. If you’ve been waiting for an opening, this might be it.

Why Fewer Buyers Are Competing With You Right Now

Every year, buyer traffic across the metro peaks in April, May, and June, then tapers off once school starts back up. Families with kids want to be settled before the first day of class, so most of them either close a deal by August or drop out of the market entirely until spring. That seasonal drop-off is exactly what makes fall home buying in the Twin Cities so appealing — you’re no longer competing with the entire pool of spring shoppers for the same handful of listings.

Minneapolis Area REALTORS® data shows housing supply climbing to its highest level in seven years this summer, with months of inventory up more than 10% year-over-year as of the July report. More homes on the market combined with fewer active buyers is a combination Twin Cities shoppers haven’t seen much of since before the pandemic, and it tends to hold through the fall selling season.

The Sellers Still Listing in Fall Are Often the Most Motivated

Think about who lists a home in October instead of April. Some people are relocating for a new job that starts soon. Some are closing on a new construction home and need their current one sold. Others already tried to sell in spring, didn’t get the offer they wanted, and are back on the market heading into a slower season — which usually means they’re more open to negotiating on price, closing costs, or timeline than they were three months ago.

That doesn’t mean every fall seller is desperate — plenty are simply pricing realistically for the season. But as a buyer, you’re far more likely to find room to negotiate on a Twin Cities listing in October than you were during the multiple-offer scrum of May.

Twin Cities Fall Buying Snapshot

Metro-area homes sold in roughly 20 days on average this summer, with buyers making about 3 offers before winning — but that pace typically eases as fall progresses and buyer traffic thins out. Months of housing supply were up over 10% year-over-year as of the most recent Minneapolis Area REALTORS® report, and the average 30-year mortgage rate has been hovering in the mid-6% range (Freddie Mac PMMS, late August 2026). Figures are directional averages for the 7-county metro and will vary by community and price point.

Top Reasons Fall Is a Smart Time to Buy in the Twin Cities

1.

Less bidding-war pressure

With fewer buyers touring homes each weekend, you’re less likely to find yourself in a multiple-offer situation, which means more room to negotiate price and terms instead of just trying to win.

2.

More time to think and negotiate

Spring listings can get an offer within a day or two. Fall listings tend to sit a bit longer, giving you breathing room to schedule an inspection, sleep on a decision, and negotiate repairs or credits without feeling rushed.

3.

A chance to see the home’s true condition

Fall is when Minnesota homes show their weak spots — you can see how gutters and drainage handle wet leaves and early rain, and get a real read on the furnace before you need it in January.

4.

Movers, lenders, and inspectors have more availability

Moving companies, home inspectors, and even lenders are less slammed once the summer rush ends, which often means faster scheduling and more attention on your file.

What to Watch For as a Fall Buyer

Fall home buying in the Twin Cities isn’t without trade-offs. Your pool of homes to choose from will naturally be smaller than it was in May, since fewer sellers list this time of year. Mortgage rates have been sitting in the mid-6% range recently, so it’s worth getting pre-approved and shopping more than one lender for your rate rather than assuming it’ll be similar to what a friend got a year or two ago. And don’t let a slower market talk you into skipping the fundamentals — a full inspection and a clear-eyed look at the school district, commute, and neighborhood still matter just as much in October as they do in June.

If winter is genuinely your target instead, it’s worth reading up on how buying later in the season compares, since the calculus shifts again once the ground freezes and the holidays hit.

Fall Home Buying in the Twin Cities: Quick Answers

Is fall a good time to buy a house in Minnesota?

For many buyers, yes. Fall typically brings less competition, more negotiating room, and sellers who are motivated to close before winter, though there are usually fewer listings to choose from than in spring.

Do home prices drop in the fall in the Twin Cities?

Prices don’t usually fall dramatically, but list-to-sale price ratios tend to soften and sellers become more open to negotiating below asking price compared to the peak of spring and summer.

Should I wait until spring to get more homes to choose from?

Waiting means facing more competition and typically higher prices when spring buyer demand returns. Many buyers find that a smaller pool of fall listings with far less competition is a better trade-off than a crowded spring market.

Ready to Take Advantage of the Fall Market?

Less competition only helps you if you’re working with an agent who knows how to use it — someone who’ll tell you when a fall seller has room to negotiate and when a listing is priced fairly from the start. MinnMatch is a free matchmaking service that pairs you with a vetted local agent who knows your target neighborhood and this season’s market cold. Find your match today and head into fall with someone in your corner who actually knows the Twin Cities.

Negotiating Repairs After a Home Inspection in Minnesota in 2026: What’s Reasonable to Ask

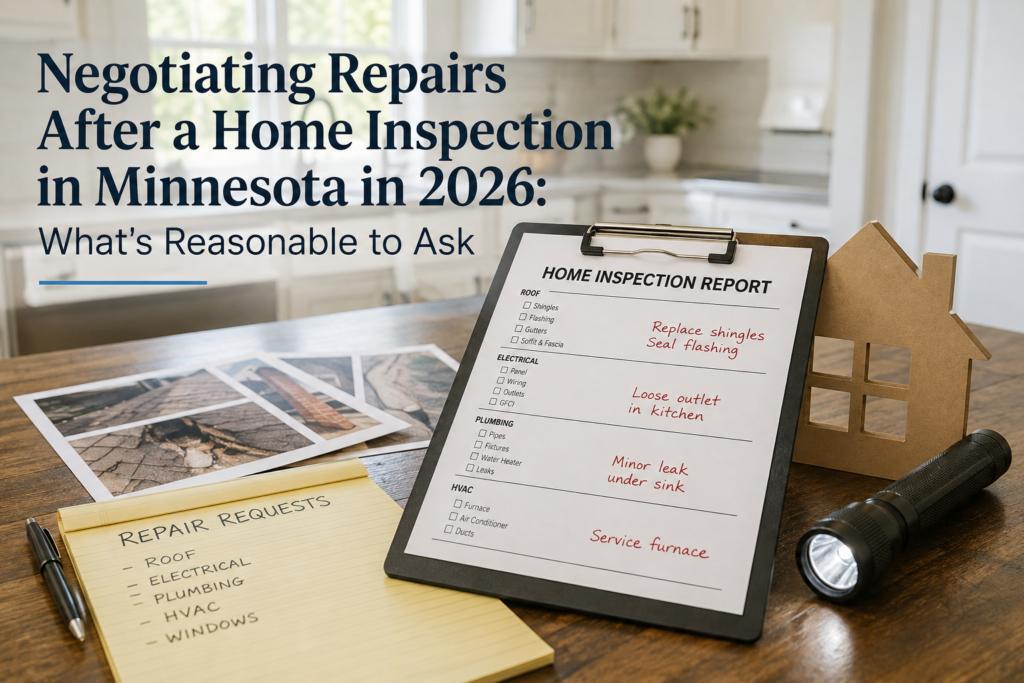
Home inspection report on clipboard with handwritten repair requests for roof, electrical, plumbing, and HVAC in a Minnesota kitchen

The inspection is done, the report has landed in your inbox, and it’s twelve pages of photos, moisture readings, and phrases like “recommend further evaluation.” Take a breath. Almost every Minnesota home inspection turns up something — that’s what inspectors are for. The real skill isn’t finding a home with zero issues; it’s knowing which ones are worth a fight and which ones you should let go so the deal, and the relationship with your seller, stays intact. Negotiating repairs after inspection is one of the most consequential — and most misunderstood — steps in buying a house here, and getting it right takes a mix of local knowledge and a level head.

What “Reasonable” Actually Means When Negotiating Repairs After Inspection

Minnesota’s standard inspection contingency isn’t a punch list — it’s a safety valve. It exists so a buyer isn’t stuck closing on a house with a cracked foundation or knob-and-tube wiring they didn’t know about. That framing matters when you’re deciding what to negotiate. Safety issues, code violations, and anything affecting the structure, roof, electrical, plumbing, or major systems are almost always fair game. Peeling paint on a 1920s trim board, a scuffed garage floor, or a dated bathroom vanity generally aren’t — those are things you accounted for (or should have) when you made your offer.

A useful gut check: would this issue affect whether the home is safe, habitable, or insurable? If yes, it belongs in your repair request. If it’s really about taste or wear you noticed after the fact, it’s better handled with a contractor after closing than with a seller before it. This is the mental filter to run through every item on the report before you start negotiating repairs after inspection with the seller.

The Issues Minnesota Inspectors Flag Most Often

Some findings show up again and again in Twin Cities inspection reports, and each one carries its own negotiating logic:

Radon. This is the one that catches out-of-state buyers off guard. Roughly two in five Minnesota homes test above the EPA’s action level of 4.0 pCi/L, largely because of the uranium-bearing glacial soils under most of the state. A high radon reading isn’t a reason to panic or walk — mitigation systems typically run in the low four figures and work well. It is, however, a completely standard and reasonable thing to ask a seller to install or credit before closing.

Roof and ice dam damage. Our freeze-thaw winters are hard on roofs, and inspectors regularly flag ice-dam-related shingle damage, soffit rot, or inadequate attic ventilation. If a roof is at or near the end of its life, or there’s evidence of active water intrusion, that’s a legitimate repair or credit request — not a nitpick.

Aging mechanicals. A furnace, water heater, or electrical panel that’s original to a 1970s or ’80s home and clearly failing is fair to negotiate. One that’s simply older but still functioning and passing inspection usually isn’t — you can’t ask a seller to replace something just because it’s not new.

Sump pumps and water intrusion. With our water table and clay-heavy soils in parts of the metro, a nonfunctional sump pump or signs of past basement water are worth addressing before closing, especially in homes near lakes or in low-lying areas.

Older wiring and plumbing. In pre-1960s homes across South Minneapolis, St. Paul, and other established neighborhoods, knob-and-tube wiring or galvanized plumbing can affect insurability, which gives you real negotiating leverage — insurers sometimes won’t write a policy until it’s addressed.

Repairs, Credits, or a Price Reduction: Choosing Your Ask

Once you’ve decided what’s worth raising, you generally have three ways to ask for it, and each has trade-offs:

Ask the seller to complete the repair. This works well for defined, licensed-contractor jobs — a radon mitigation system, an electrical panel upgrade — where you want it done correctly before you own the problem. The trade-off is quality control: you’re trusting the seller to hire someone competent on a deadline, and you should ask for receipts or a licensed contractor’s invoice as proof.

Ask for a closing cost credit. This is often the cleanest option — the seller reduces what they’re contributing at closing, and you handle the repair yourself with a contractor you trust, on your own timeline. It’s usually the preferred route for anything where quality of work matters more than speed.

Ask for a straight price reduction. Less common, but sometimes used for bigger-ticket items where both sides just want to simplify and move forward without haggling over contractor estimates.

Whichever route you choose, get a couple of contractor quotes before you name a number. A repair request backed by a real estimate is taken far more seriously than one based on a guess — and it’s one of the simplest ways to strengthen your position when negotiating repairs after inspection.

Structuring the Ask Without Blowing Up the Deal

Minnesota purchase agreements built on the standard Minnesota Association of REALTORS® forms give you a defined inspection contingency window, and your repair request typically goes to the seller as a formal amendment within that timeframe. A few habits make the process smoother for everyone:

Prioritize your list. Leading with three or four legitimate, well-documented issues lands better than a fifteen-item wish list that buries the real concerns in cosmetic noise. Sellers — and their agents — tend to respond defensively to a laundry list and reasonably to a short, specific one.

Know your walk-away point before you send the request. If the seller declines or only partially agrees, Minnesota’s inspection contingency generally allows you to cancel the purchase agreement and have your earnest money returned, provided you’re acting within the contingency period. Deciding in advance what you’d actually walk away from keeps the negotiation from becoming personal.

Expect some back-and-forth. In a balanced or buyer-leaning market, sellers are often willing to address safety and major-system items to keep the deal moving. In a competitive, multiple-offer market, buyers sometimes waive repair requests entirely to stay attractive — which is exactly why it’s worth thinking through your inspection strategy before you write an offer, not after. Redfin’s market data can give you a read on how much negotiating leverage buyers currently have in your area before you decide how hard to push.

Let Someone Who Negotiates This Weekly Handle It

Reading an inspection report is one thing; knowing what a Wayzata seller will actually agree to versus what a St. Paul seller will, or how a listing agent typically responds to a radon credit request, is a different kind of knowledge — the kind that comes from doing this negotiation dozens of times a year in your specific market. That’s exactly the gap a locally connected buyer’s agent closes. MinnMatch’s free agent-matching service connects you with a vetted Twin Cities agent who knows how repair negotiations actually play out neighborhood by neighborhood — not just what the contract allows, but what’s realistic to ask for and win. If you’re not sure how the matching process works, our how it works page walks through it in a couple of minutes, and there’s never a cost to you as a buyer.

Fixer-Upper vs. Move-In Ready in the Twin Cities in 2026: Which Is the Better Investment?

Fixer-upper vs. move-in ready home comparison in the Twin Cities

If you’re house hunting in the Twin Cities this year, you’ve probably stood in a dated kitchen at some point and wondered: is this a diamond in the rough, or a money pit with new carpet? The fixer-upper vs. move-in ready question is one of the most common forks in the road for Minnesota buyers in 2026, and with mortgage rates still hovering in the mid-6% range and metro inventory finally loosening up, the answer isn’t as obvious as it used to be. Whether the better investment is the home that needs work or the one that’s already done depends on your budget, your timeline, and how much Minnesota winter you’re willing to spend under a tarp.

What “Fixer-Upper” and “Move-In Ready” Actually Mean Right Now

In the Twin Cities, a huge share of the housing stock dates back to the 1950s through the 1980s, which means “fixer-upper” can mean anything from a home that just needs cosmetic updates — paint, flooring, a kitchen refresh — to a full gut job with knob-and-tube wiring or a leaking cast iron sewer line hiding behind the walls. Move-in ready, meanwhile, typically means a home where the roof, mechanicals, and major systems have already been updated, even if the finishes aren’t your personal style. The metro’s inventory has grown noticeably this year, with the number of homes for sale climbing to roughly 10,900 across the 13-county area, giving buyers more of both types to choose from than they’ve seen in years.

That added supply matters, because it means buyers weighing fixer-upper vs. move-in ready options aren’t forced into a single lane the way they were in tighter markets. You have room to actually compare, rather than grabbing whatever hits the market first.

The Math: Renovation Costs vs. the Price Premium for Move-In Ready

This is where a lot of buyers get tripped up, because renovation math in the Twin Cities doesn’t always match what you’ll see on national remodeling shows. Local kitchen remodels commonly run $50,000 to $175,000 or more depending on scope and finishes, bathroom remodels typically land between $30,000 and $85,000, and a basement finish can run $45,000 to $200,000+. Twin Cities pricing tends to run higher than national averages, partly because of an older housing stock that often needs electrical panel or plumbing updates before the “pretty” work can even start.

On the resale side, a mid-range kitchen remodel has historically recouped somewhere in the 75–85% range at resale, while smaller, cosmetic-only updates can return 90% or more. Compare that to the current metro median sale price of around $400,000–$410,000, and you can start running your own back-of-napkin math: is the discount on the fixer-upper larger than what you’d spend to bring it up to move-in-ready condition, plus a buffer for surprises? In most cases in this market, the discount needs to be meaningful — not just a few thousand dollars — for a fixer-upper to pencil out as the better investment.

Financing the Gap: Rates, Renovation Loans, and Timeline Reality

Financing is where the fixer-upper vs. move-in ready decision gets real. As of late July 2026, the 30-year fixed mortgage rate has been sitting around 6.58%, a level that’s held fairly steady over the past several weeks. For a fixer-upper, you’re often financing two things at once — the purchase and the renovation — which usually means a renovation-specific loan product (like an FHA 203(k) or a conventional renovation loan) rather than just a standard purchase mortgage. These loans typically carry more paperwork, more inspections, and a longer closing timeline than a conventional purchase, so budget extra weeks, not days.

Move-in ready homes skip that complexity entirely — you close, you move in, and your mortgage payment is your only monthly wildcard. If your timeline is tight (a job relocation, a lease ending, kids starting school), that predictability alone can outweigh a lower purchase price on a project home.

Where Fixer-Uppers Make Sense in the Twin Cities — and Where They Don’t

Location changes this calculus quite a bit. In established, high-demand areas where land and lot value carry a lot of the price, a dated home on a great block can be a smart renovation candidate, because you’re paying primarily for location and can add value through updates. In faster-moving suburban markets with newer housing stock, the “fixer-uppers” you find are often outliers for a reason — deferred maintenance that’s more expensive to fix than the discount suggests. It’s also worth noting that months of supply varies a lot by price range in the metro right now, with mid-priced homes moving faster than either the lower or upper ends, which affects how much negotiating room you’ll actually have on a project home.

The honest answer to fixer-upper vs. move-in ready isn’t universal — it’s specific to the suburb, the price range, and the individual house. A local agent who knows which streets have aging infrastructure and which renovations actually hold their value in your target neighborhood is worth far more here than a national rule of thumb.

Fixer-Upper vs. Move-In Ready: Which Is the Better Investment for You?

There’s no universal winner in the fixer-upper vs. move-in ready debate — just a better fit for your budget, your timeline, and your appetite for a construction dumpster in the driveway through a Minnesota winter. What matters most is running the real numbers on a specific house, not a hypothetical one, before you fall in love with either the discount or the granite countertops.

That’s exactly the kind of judgment call a good local agent helps with every day. If you’re trying to figure out whether a specific fixer-upper is a smart bet or a slow-motion budget blowout, MinnMatch can match you with a Twin Cities agent who knows the renovation history and resale patterns of the neighborhoods you’re considering — for free. Curious how the matching process works? Here’s how MinnMatch works.

Sources: Freddie Mac Primary Mortgage Market Survey, Minneapolis Area Realtors Market Data, Redfin Minneapolis Housing Market.

HOA or No HOA? What Minnesota Buyers in 2026 Need to Know Before Making an Offer

Split graphic comparing HOA townhome community and non-HOA single-family home with a signpost pointing each direction

You found the layout you want, the price feels right, and then the listing mentions it: HOA. For a lot of Twin Cities buyers, that one line raises more questions than it answers. Is an HOA in Minnesota a dealbreaker, a convenience, or just part of the territory once you start touring townhomes and condos? The honest answer is “it depends” — but 2026 is actually a meaningful year to be asking, because Minnesota just overhauled the law that governs how an HOA in Minnesota operates. Here’s what buyers need to understand before writing an offer.

What an HOA in Minnesota Actually Is (And Who It Governs)

Most homeowners associations in Minnesota — whether attached to a townhome, condo, or single-family planned community — fall under the Minnesota Common Interest Ownership Act, commonly shortened to MCIOA. This is the state law that has applied automatically to common interest communities created after June 1, 1994, and it sets the ground rules for how an HOA collects dues, manages shared property, and communicates with owners. Older associations aren’t automatically covered, though many have voluntarily opted in over the years. If a property you’re considering has an association, that association almost certainly answers to MCIOA, and understanding the basics of that law is one of the more useful things a Minnesota buyer can do before making an offer.

In practice, an HOA takes on responsibilities you’d otherwise handle yourself: exterior maintenance, landscaping, snow removal, insurance on shared structures, and upkeep of amenities like pools or clubhouses. In exchange, you agree to pay dues, follow the community’s rules, and accept that some decisions about your building or block are made collectively rather than individually. For buyers weighing a lower-maintenance lifestyle against wanting full control of their property, that trade-off is really the heart of the HOA question.

What an HOA in Minnesota Actually Costs You Each Month

This is where buyers are often caught off guard, and the numbers vary enough that a single figure would be misleading. Metro-wide reporting on 2025 sales put the median HOA fee across the Twin Cities at roughly $278 a month — a notably higher share of the typical house payment than most U.S. metros see. Townhome-specific associations in the metro tend to run higher than that median, commonly landing somewhere in the $300–$450 range, especially in communities with more shared amenities. Condo dues can climb well beyond that: buildings with elevators, structural reserves, or full-service amenities have pushed some Twin Cities condo fees close to $1,000 a month.

Because the range is this wide, don’t anchor to a single “average” when you’re evaluating a specific property. Ask for the association’s most recent financials and reserve study, and look at the trend over the past three to five years, not just the current monthly number. A fee that looks reasonable today can jump significantly if the association has been underfunding its reserves — which is exactly the kind of risk Minnesota’s new rules are trying to catch earlier.

Minnesota’s New HOA Rules: What Changed in 2026

2026 is a genuinely important year for anyone buying into a homeowners association here. Minnesota lawmakers passed a significant update to MCIOA this session — sometimes referred to as an HOA “bill of rights” — with most provisions set to take effect January 1, 2027, giving associations roughly seven months to come into compliance. Buyers closing between now and then should know the changes are coming, because they’ll shape how the association you’re joining operates going forward.

Among the more buyer-relevant pieces: associations will face new transparency requirements around board meetings and documents, competitive-bidding rules for larger maintenance contracts, limits on fines, added protections against retaliation, and a streamlined process for terminating an HOA under certain conditions. Existing MCIOA requirements already in place include annual financial statements (with a CPA review unless owners waive it), reserve fund reviews at least every three years, and a resale disclosure certificate that sellers must provide when a unit changes hands. That resale certificate is one of the single most useful documents a buyer can request — it typically spells out current dues, any pending special assessments, and the financial health of the association.

The state’s Department of Commerce keeps current guidance on MCIOA and common interest communities, and it’s worth a look if you want the details straight from the source rather than secondhand. You can find that at the Minnesota Department of Commerce’s common interest community resource page.

HOA or No HOA: How to Decide What’s Right for You

There’s no universally right answer here — it comes down to what kind of homeowner you want to be. An HOA can be a genuinely good fit if you travel often, want predictable (if sometimes pricier) monthly costs instead of surprise repair bills, or specifically want amenities like a pool, fitness room, or maintained common grounds without personally managing any of it. Nationally, homes in HOA communities have tended to carry a modest price premium over similar non-HOA homes, which some buyers see as a sign the arrangement holds resale value — a data point tracked at the national level by the U.S. Census Bureau’s housing statistics.

On the other side, if you want full control over your landscaping, exterior paint color, or whether you can park a boat in the driveway, an association’s rules can feel restrictive fast. And as Twin Cities condo owners have learned recently, rising dues can make a property harder to resell, particularly at the entry-level price point where buyers are most fee-sensitive. If you’re comparing a specific HOA property against a non-HOA alternative, it often helps to look at recent comparable sales and neighborhood context — resources like Redfin’s neighborhood and market data can be useful for that kind of side-by-side comparison, alongside whatever your agent pulls directly from the MLS.

Whichever direction you lean, read the governing documents before you write an offer — not after. Declarations, bylaws, rules, and the most recent meeting minutes will tell you far more about day-to-day life in that community than the listing sheet ever will.

Getting the Right Guidance for Your Situation

HOA questions are exactly the kind of thing that benefit from someone who knows the specific building, block, or association you’re considering — not just general rules of thumb. A Twin Cities agent who regularly works in a given community will already know which associations are well-run, which have had special assessments, and which fee ranges are typical for that neighborhood. If you’re weighing an HOA property and want that kind of on-the-ground read before you make an offer, MinnMatch can match you with a local agent who’s handled exactly this kind of decision before.

Lock Your Rate or Float? What Minnesota Home Buyers Should Know About Mortgage Rates in 2026

Notebook comparing lock vs. float mortgage rate options with MinnMatch mug and Twin Cities homes

If you’re shopping for a home in the Twin Cities right now, you’ve probably noticed mortgage rates have been anything but boring lately. They ticked up two weeks in a row through late July, and the Federal Reserve’s next meeting could nudge them further in either direction. That leaves a lot of Minnesota buyers asking the same question: should you lock your mortgage rate the moment you get an offer, or float it and hope for a better number before closing? There’s no universal right answer, but there is a smart way to think through it — and that’s what we’re walking through here.

Where Minnesota Mortgage Rates Stand Right Now

As of the most recent Freddie Mac Primary Mortgage Market Survey, the average 30-year fixed rate mortgage sits at 6.58%, up slightly from 6.55% the week before and 6.49% the week before that. Compare that to a year ago, when the 30-year average was running closer to 6.74%, and you can see rates have actually improved a bit over the past twelve months even with this recent upward drift. The 15-year fixed rate, often used by move-up buyers and downsizers here in the Twin Cities, is averaging just under 6%.

What does that mean if you’re house hunting in Eden Prairie, Plymouth, or South Minneapolis this summer? Mostly that rates have been trading in a fairly narrow band for a couple of months, but the direction has tilted upward recently rather than the steady drift downward a lot of buyers were hoping for. That’s exactly the kind of environment where a mortgage rate lock decision actually matters.

Locking vs. Floating: What Each Choice Really Means

A rate lock is an agreement with your lender that guarantees a specific interest rate for a set period — typically 30, 45, or 60 days — while your loan moves through underwriting to closing. Once locked, your rate won’t change even if the broader market moves, whether that’s good news or bad news for you. Most Minnesota lenders don’t charge extra for a standard lock window, though longer locks (say, 90 days for new construction) sometimes come with a small fee or slightly higher rate.

Floating means you’re choosing not to lock yet, betting that rates will drop before you need to commit. Some lenders also offer a “float-down” option, which lets you lock now but still capture a lower rate if one becomes available before closing — usually for an added fee. Floating without any safety net at all is the riskiest version of this strategy, since there’s nothing protecting you if rates move the other direction while you wait.

Why the Fed’s Late-July Meeting Matters for Your Rate Strategy

The Federal Reserve’s Federal Open Market Committee meets July 28-29, and it’s one of the more closely watched meetings of the year for anyone weighing a mortgage rate lock decision. The Fed has held its benchmark rate steady through multiple meetings in 2026, and most market pricing points to another hold this time around, though a modest increase hasn’t been ruled out given persistent inflation. Mortgage rates don’t move in lockstep with the Fed’s overnight rate, but Fed commentary and inflation data both tend to ripple through to the 30-year fixed rate within days.

Practically speaking, if you’re closing on a Twin Cities home in the next few weeks, this meeting sits right in the middle of your process. That’s a strong argument for locking sooner rather than later if you’re already comfortable with today’s rate and don’t want to be surprised by a rate hike mid-transaction. Floating through a Fed meeting is a real bet, not a guaranteed win.

How to Decide: Questions Minnesota Buyers Should Ask

There’s no single formula for the lock-or-float decision, but a few questions tend to clarify it fast:

  • How far out is your closing? The further away, the more time rates have to move — in either direction.
  • Would a small rate increase change whether the home is affordable? If your budget is tight, locking removes that variable entirely.
  • Does your lender offer a float-down option? This can be a reasonable middle ground if you want some downside protection.
  • How do you feel about today’s rate on its own merits? If it works for your monthly payment and long-term plans, waiting for a “maybe” is rarely worth the stress.

If affordability is tight either way, it’s also worth asking your lender whether you qualify for a Minnesota Housing fixed-rate loan program, which can sometimes offer more favorable terms than a standard conventional loan. Most Minnesota loan officers will tell you the same thing: rate locks exist to remove uncertainty, not to time the market perfectly. If today’s rate lets you comfortably afford the home you want, locking it in is rarely a mistake — even if rates dip slightly afterward. Chasing the absolute bottom of the market is a gamble, not a strategy.

Get Rate Guidance From an Agent Who Knows the Twin Cities Market

Mortgage rate decisions don’t happen in a vacuum — they’re tied to your timeline, your target neighborhoods, and how competitive the market is for the home you want. A great local agent will loop in a trusted lender and help you weigh the lock-or-float question against your actual purchase timeline, not just the headlines. That’s exactly the kind of personal guidance MinnMatch was built to provide. Tell us what you’re looking for and where, and we’ll hand-match you with a vetted Twin Cities agent who can help you navigate financing decisions alongside everything else. Find your agent match today, or visit how MinnMatch works to see the process from start to finish.

What Is a Comparative Market Analysis (CMA) and Why You Need One in Minnesota in 2026

Comparative market analysis report on a desk with a Minnesota home, neighborhood map, and MinnMatch coffee mug

If you’ve spent any time talking to a Twin Cities real estate agent, you’ve probably heard the term “CMA” thrown around. It sounds technical, but it’s really one of the most useful documents you’ll encounter as a buyer or seller in Minnesota’s 2026 market. A comparative market analysis takes the guesswork out of pricing by showing you, in black and white, what similar homes in your area have actually sold for. Whether you’re getting ready to list a home in Edina or you’re trying to figure out if a listing in Plymouth is priced fairly, understanding what a CMA is — and how to read one — puts you in a much stronger position.

What Exactly Is a Comparative Market Analysis?

A comparative market analysis is a report, usually prepared by a licensed real estate agent, that estimates a home’s current market value by comparing it to similar properties — often called “comps” — that have recently sold, are currently listed, or went under contract in the same area. A good CMA looks at square footage, lot size, bedroom and bathroom count, age, condition, and location, then adjusts for differences between the subject property and each comp.

In a market like the Twin Cities, where prices can shift block by block — a rambler in South Minneapolis can behave very differently than one in Prior Lake — a comparative market analysis grounds your expectations in local data instead of national headlines or a Zillow estimate. According to Minneapolis Area Realtors, local market conditions vary significantly by neighborhood and price tier, which is exactly why a CMA needs to be built from nearby, recent, and truly comparable sales rather than a citywide average.

CMA vs. Appraisal: They’re Not the Same Thing

It’s easy to confuse a comparative market analysis with a home appraisal, but they serve different purposes and come from different people. A CMA is typically prepared by your real estate agent, is free, and is meant to help set a listing price or shape an offer. An appraisal is completed by a state-licensed, independent appraiser, usually costs a few hundred dollars, and is required by your lender before closing to confirm the home is worth what you’re paying for it.

Think of it this way: a CMA is a strategic estimate built for decision-making before you list or offer, while an appraisal is a formal, regulated valuation used to protect the lender’s investment. The two often land in a similar range, but they’re not interchangeable, and a CMA is never a substitute for the appraisal your mortgage will require.

Why Sellers Should Start Here, Not With a Number They Have in Mind

Plenty of Twin Cities sellers walk into the process with a price already in their head, often based on what a neighbor’s house sold for years ago or what a home improvement show made pricing look like. A comparative market analysis replaces that gut feeling with current, local evidence. It’s the starting point for a listing strategy — before staging decisions, before marketing photos, before the “For Sale” sign goes in the yard.

We’ll go deep on pricing strategy and how to interpret specific comps in an upcoming article, but the short version is this: a CMA is the foundation everything else gets built on. If you’re weighing whether to list this year, our seller resources page is a good next stop, and connecting with a local agent through MinnMatch’s free agent-matching service is the easiest way to get a CMA built specifically for your address, not a generic estimate.

Buyers Need a CMA Too — Here’s Why

A comparative market analysis isn’t just a seller’s tool. Before you write an offer on a home in Minnetonka or Eden Prairie, a buyer’s agent can run a CMA to tell you whether the asking price actually lines up with what similar homes have sold for recently. That’s especially valuable in a market where a well-staged listing photo or an eager seller’s price can make a home look like a deal — or a stretch — when the comps tell a different story.

A buyer-side CMA also gives you real leverage in negotiations. Instead of an offer based on a feeling, you can point to actual recent sales nearby. If you’re just starting to look, our buyer resources page walks through what else to expect, and Redfin can be a helpful place to sanity-check recent sale prices in a neighborhood you’re considering, alongside the more detailed comps your agent pulls.

Getting an Accurate CMA in the Twin Cities Market

The accuracy of a comparative market analysis depends entirely on the person building it. An agent who knows a specific pocket of the Twin Cities — the difference between a Wayzata lake lot and one a few blocks off the water, or why one South Minneapolis block sells faster than the one next to it — will build a far more useful CMA than an automated online estimate ever could. Housing conditions can also shift with financing programs and affordability trends; resources like the Minnesota Housing Finance Agency track statewide affordability data that can add helpful context to a hyper-local CMA.

This is really where local expertise makes or breaks the number. An out-of-area agent, or a generic online tool, simply won’t know the nuances that move value street by street across the metro.

Get a CMA From an Agent Who Knows Your Neighborhood

Whether you’re preparing to sell or trying to make sense of a listing price, a comparative market analysis is only as good as the agent behind it. MinnMatch connects Twin Cities buyers and sellers with handpicked local agents — for free — so you get a CMA built on real neighborhood knowledge, not guesswork. Find your agent match today and get a clear, accurate picture of what your home — or your next one — is really worth.