August 2026 Twin Cities Real Estate Market: Late Summer Trends, Inventory & What’s Shifting

MinnMatch coffee mug and August 2026 Twin Cities real estate market update notebook overlooking the Minneapolis skyline

Summer isn’t over yet, but the Twin Cities real estate market is already showing the first signs of its late-season shift. Prices are still climbing, but at a more measured pace than the frenzied years of the past decade. Inventory keeps building. And mortgage rates, while still elevated, have settled into a range buyers are starting to plan around rather than wait out. If you’re weighing a move this fall, here’s what the latest numbers say about where things actually stand right now.

Home Prices Are Still Rising — Just Not Like They Used To

The median sales price across the 16-county Twin Cities metro reached $410,000 in June 2026, the most recent full month of closed-sale data available, up 2.1% from a year earlier, according to Minneapolis Area Realtors® (MAAR) data pulled from NorthstarMLS. The average sales price came in at $492,008, up a more modest 0.8% year-over-year — a gap that suggests the priciest segment of the market is cooling faster than the entry- and mid-tier segments that make up most first-time buyer activity. Price per square foot climbed to $223, up 2.0% from last June. None of this points to a market losing steam; it points to one settling into a steadier, more sustainable rhythm after several years of sharper swings.

Inventory Keeps Climbing, and That’s Good News for Buyers

Buyers heading into late summer have more to choose from than they did a year ago. Active inventory stood at 10,897 homes at the end of June, up 5.1% year-over-year, while new listings jumped 10.5% to 7,268 for the month — the strongest new-listing growth of any month so far in 2026. Months of supply ticked up to 2.8, still short of the 5-to-6-month range that typically defines a balanced market, but the highest reading of this year. For buyers who’ve felt boxed out over the past few summers, this is the most breathing room the Twin Cities market has offered in a while.

Mortgage Rates Are Holding in the Mid-6% Range

According to Freddie Mac’s Primary Mortgage Market Survey®, the 30-year fixed rate averaged 6.66% as of July 30, 2026, up slightly from 6.58% the week before but still below the 6.72% mark from a year earlier. The 15-year fixed rate averaged 6.04% over the same period. Rates have moved in a fairly narrow band throughout July — mostly between 6.4% and 6.7% — which has given buyers something they haven’t had in a while: a rate environment stable enough to actually plan around instead of trying to time.

Homes Are Taking a Little Longer to Sell — But Sellers Are Still Winning

The average Twin Cities home took 42 days to sell in June, up 7.7% from 39 days a year ago. That’s a real shift from the sub-three-week pace of peak pandemic-era competition, but it’s still a fast market by any historical measure. Sellers are also still getting close to full asking price: homes sold for 99.6% of original list price on average in June. Closed sales jumped 10.7% year-over-year to 5,602, and pending sales rose 9.7% — both signs that buyer demand hasn’t backed off even as homes take a bit longer to find the right offer.

What This Means as Fall Approaches

Taken together, the data points to a Twin Cities real estate market that’s neither cooling off nor overheating — it’s normalizing. Rising inventory and slightly longer days on market give buyers more leverage than they’ve had in years, while steady price growth and strong percent-of-list-price figures show sellers still have the upper hand in well-priced, well-located homes. As families finish out summer and back-to-school season kicks in, expect the usual late-summer slowdown in showing traffic, followed by a typical uptick in serious, motivated buyers this fall.

Whichever Side of the Table You’re On, Timing Matters

Numbers like these tell you what the market is doing overall, but every Twin Cities suburb and neighborhood is moving at its own pace right now. If you’re trying to figure out what late-summer conditions mean for your specific street, price point, or timeline, MinnMatch can match you with a local agent who knows exactly how your area is trending — no algorithm, just a real person who knows the Twin Cities market inside and out.
Why Twin Cities Sellers Are Getting a Pre-Listing Inspection Before They List in 2026

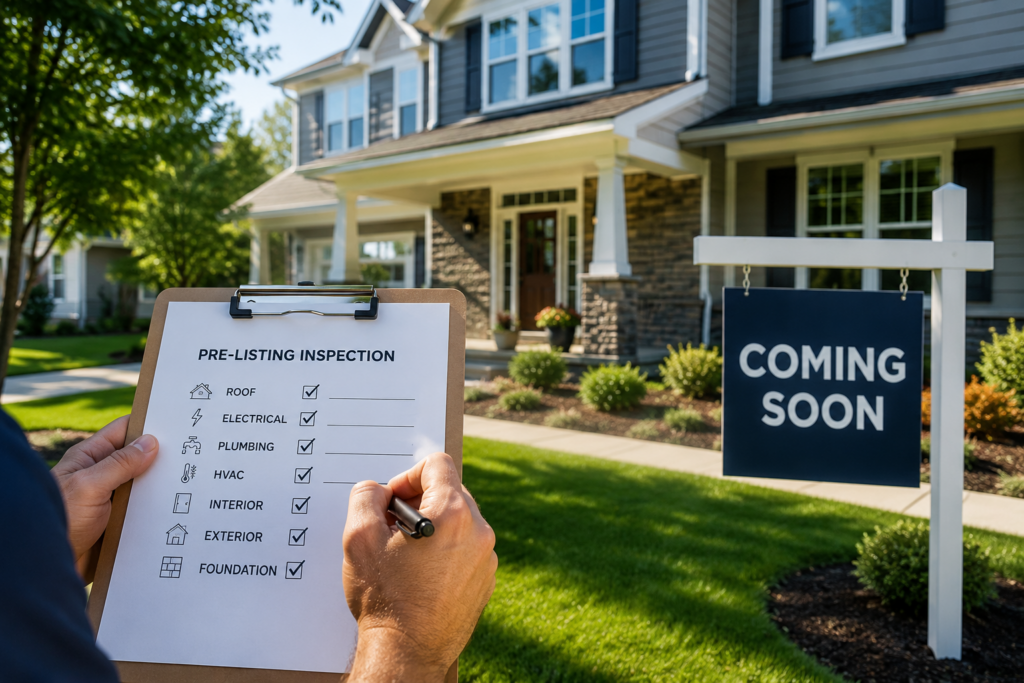
Person holding a "Pre-Listing Inspection" checklist clipboard in front of a Twin Cities home with a "Coming Soon" real estate sign

If you’re getting ready to sell a home in the Twin Cities this year, there’s a decision that comes up long before your first showing: should you pay for a pre-listing inspection? It’s not required, and plenty of Minnesota sellers skip it. But more and more agents around the metro are recommending it upfront, especially in a market where buyers are cautious and inspection-related renegotiations can derail a deal. Here’s what a pre-listing inspection actually does for you, what it tends to cost, and how to decide if it’s worth it for your sale.

What Is a Pre-Listing Inspection, Exactly?

A pre-listing inspection is the same type of general home inspection a buyer would order, except you hire the inspector yourself, before the home ever hits the market. A licensed inspector walks the property top to bottom — roof, foundation, electrical, plumbing, HVAC, windows, and more — and hands you a full report of what they find. Some Twin Cities sellers stop there. Others use the report to get ahead of repairs, adjust their price, or simply have documentation ready to share with buyers.

It’s a growing trend, but it’s still very much optional in Minnesota. Nothing in state law requires a seller to have their home inspected before listing — Minneapolis Area Realtors notes that the decision is entirely up to the seller and their agent’s recommendation based on the home’s age and condition.

The Real Benefit: Fewer Surprises After You’re Under Contract

The biggest advantage of a pre-listing inspection isn’t the report itself — it’s timing. When a buyer’s inspector finds a cracked heat exchanger or an aging roof three weeks into a purchase agreement, you’re negotiating repairs or a price reduction under pressure, often with a closing date already on the calendar. When you get that same information before you list, you get to decide, on your own timeline, whether to fix it, price around it, or disclose it and move forward.

That matters a lot in the Twin Cities right now. Inventory has been tight enough in several suburbs that sellers don’t want to lose a buyer over a repair negotiation that could have been settled — or avoided entirely — before the home ever went live.

Pricing Confidence and Fewer Renegotiations

A home’s condition is a pricing input, not just a disclosure issue. Sellers who complete a pre-listing inspection often price their home more accurately from day one, because they’re not guessing at what a buyer’s inspector might turn up. If the report comes back clean, that’s a selling point you can lean into. If it surfaces a few items, you can factor those into your list price rather than getting hit with a lowball renegotiation after you’ve already accepted an offer.

It also tends to shorten the path to closing. Buyers and their agents read confidence into a seller who’s already done the homework — it signals there’s nothing being hidden, which can mean fewer contingencies and a smoother path to the closing table.

What It Costs and How to Fit It Into Your Timeline

Most general home inspections in the Twin Cities run somewhere between $300 and $600, depending on the size and age of the home, with additional cost for add-ons like radon testing or a sewer scope — both common requests in older Minnesota housing stock. Plan on scheduling it 2–4 weeks before you intend to list, which gives you time to review the report, get repair quotes if needed, and decide on next steps without rushing.

One thing to flag with your agent: Minnesota’s seller disclosure law still requires you to disclose known material defects, whether or not you order a pre-listing inspection. Getting one doesn’t create new disclosure obligations — it just means you’re finding out about issues on your own schedule instead of a buyer’s.

Is a Pre-Listing Inspection Right for Your Sale?

It’s not a fit for every seller. If your home is newer, well-maintained, and you’re confident in its condition, the added cost may not move the needle much. But for older homes, homes that have been rented for years, or homes where you suspect there could be deferred maintenance, a pre-listing inspection can be the difference between a smooth sale and a stressful renegotiation. According to Redfin’s seller resources, inspection issues remain one of the most common reasons a deal falls through or gets re-negotiated after going under contract — which is exactly the scenario a pre-listing inspection is designed to prevent.

The best way to decide is to talk it through with an agent who knows your specific home and neighborhood — not a generic rule of thumb.

Get Matched With an Agent Who’ll Give You a Straight Answer

Whether a pre-listing inspection makes sense for your home depends on its age, condition, and your local market — the kind of judgment call a good local agent is built for. MinnMatch can match you with a vetted Twin Cities agent who’ll walk through your specific situation and help you decide whether a pre-listing inspection is worth it before you list. Curious how the matching process works? Here’s how it works — and it’s free for sellers.

Fixer-Upper vs. Move-In Ready in the Twin Cities in 2026: Which Is the Better Investment?

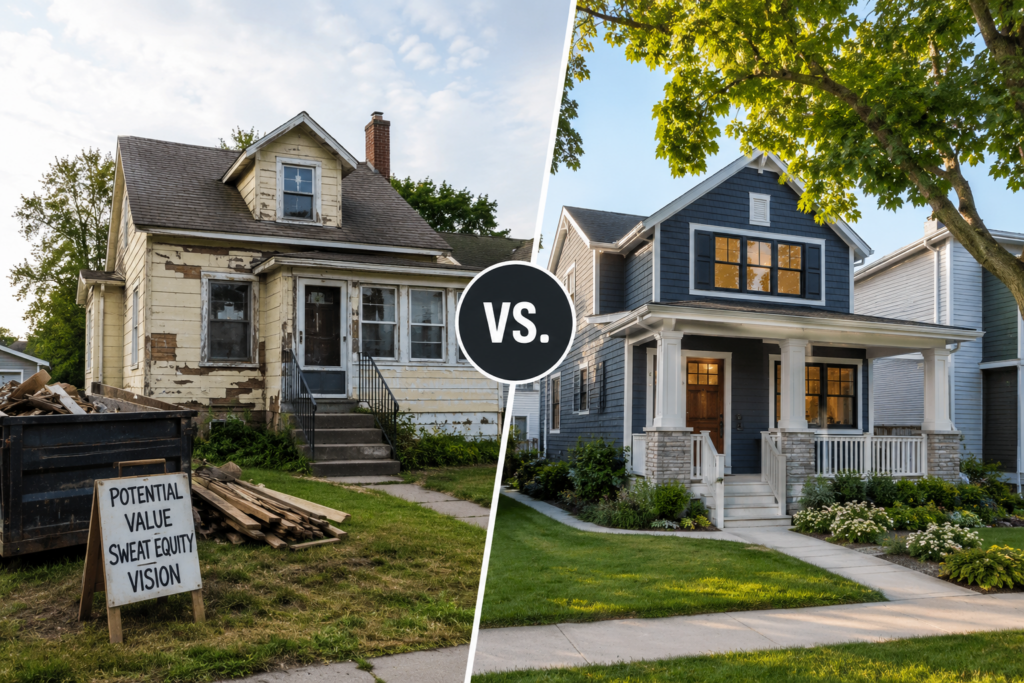
Fixer-upper vs. move-in ready home comparison in the Twin Cities

If you’re house hunting in the Twin Cities this year, you’ve probably stood in a dated kitchen at some point and wondered: is this a diamond in the rough, or a money pit with new carpet? The fixer-upper vs. move-in ready question is one of the most common forks in the road for Minnesota buyers in 2026, and with mortgage rates still hovering in the mid-6% range and metro inventory finally loosening up, the answer isn’t as obvious as it used to be. Whether the better investment is the home that needs work or the one that’s already done depends on your budget, your timeline, and how much Minnesota winter you’re willing to spend under a tarp.

What “Fixer-Upper” and “Move-In Ready” Actually Mean Right Now

In the Twin Cities, a huge share of the housing stock dates back to the 1950s through the 1980s, which means “fixer-upper” can mean anything from a home that just needs cosmetic updates — paint, flooring, a kitchen refresh — to a full gut job with knob-and-tube wiring or a leaking cast iron sewer line hiding behind the walls. Move-in ready, meanwhile, typically means a home where the roof, mechanicals, and major systems have already been updated, even if the finishes aren’t your personal style. The metro’s inventory has grown noticeably this year, with the number of homes for sale climbing to roughly 10,900 across the 13-county area, giving buyers more of both types to choose from than they’ve seen in years.

That added supply matters, because it means buyers weighing fixer-upper vs. move-in ready options aren’t forced into a single lane the way they were in tighter markets. You have room to actually compare, rather than grabbing whatever hits the market first.

The Math: Renovation Costs vs. the Price Premium for Move-In Ready

This is where a lot of buyers get tripped up, because renovation math in the Twin Cities doesn’t always match what you’ll see on national remodeling shows. Local kitchen remodels commonly run $50,000 to $175,000 or more depending on scope and finishes, bathroom remodels typically land between $30,000 and $85,000, and a basement finish can run $45,000 to $200,000+. Twin Cities pricing tends to run higher than national averages, partly because of an older housing stock that often needs electrical panel or plumbing updates before the “pretty” work can even start.

On the resale side, a mid-range kitchen remodel has historically recouped somewhere in the 75–85% range at resale, while smaller, cosmetic-only updates can return 90% or more. Compare that to the current metro median sale price of around $400,000–$410,000, and you can start running your own back-of-napkin math: is the discount on the fixer-upper larger than what you’d spend to bring it up to move-in-ready condition, plus a buffer for surprises? In most cases in this market, the discount needs to be meaningful — not just a few thousand dollars — for a fixer-upper to pencil out as the better investment.

Financing the Gap: Rates, Renovation Loans, and Timeline Reality

Financing is where the fixer-upper vs. move-in ready decision gets real. As of late July 2026, the 30-year fixed mortgage rate has been sitting around 6.58%, a level that’s held fairly steady over the past several weeks. For a fixer-upper, you’re often financing two things at once — the purchase and the renovation — which usually means a renovation-specific loan product (like an FHA 203(k) or a conventional renovation loan) rather than just a standard purchase mortgage. These loans typically carry more paperwork, more inspections, and a longer closing timeline than a conventional purchase, so budget extra weeks, not days.

Move-in ready homes skip that complexity entirely — you close, you move in, and your mortgage payment is your only monthly wildcard. If your timeline is tight (a job relocation, a lease ending, kids starting school), that predictability alone can outweigh a lower purchase price on a project home.

Where Fixer-Uppers Make Sense in the Twin Cities — and Where They Don’t

Location changes this calculus quite a bit. In established, high-demand areas where land and lot value carry a lot of the price, a dated home on a great block can be a smart renovation candidate, because you’re paying primarily for location and can add value through updates. In faster-moving suburban markets with newer housing stock, the “fixer-uppers” you find are often outliers for a reason — deferred maintenance that’s more expensive to fix than the discount suggests. It’s also worth noting that months of supply varies a lot by price range in the metro right now, with mid-priced homes moving faster than either the lower or upper ends, which affects how much negotiating room you’ll actually have on a project home.

The honest answer to fixer-upper vs. move-in ready isn’t universal — it’s specific to the suburb, the price range, and the individual house. A local agent who knows which streets have aging infrastructure and which renovations actually hold their value in your target neighborhood is worth far more here than a national rule of thumb.

Fixer-Upper vs. Move-In Ready: Which Is the Better Investment for You?

There’s no universal winner in the fixer-upper vs. move-in ready debate — just a better fit for your budget, your timeline, and your appetite for a construction dumpster in the driveway through a Minnesota winter. What matters most is running the real numbers on a specific house, not a hypothetical one, before you fall in love with either the discount or the granite countertops.

That’s exactly the kind of judgment call a good local agent helps with every day. If you’re trying to figure out whether a specific fixer-upper is a smart bet or a slow-motion budget blowout, MinnMatch can match you with a Twin Cities agent who knows the renovation history and resale patterns of the neighborhoods you’re considering — for free. Curious how the matching process works? Here’s how MinnMatch works.

Sources: Freddie Mac Primary Mortgage Market Survey, Minneapolis Area Realtors Market Data, Redfin Minneapolis Housing Market.

Lake Minnetonka Mid-Summer 2026: Why Serious Buyers Are Still Shopping Right Now

Lakefront patio with docked boats on Lake Minnetonka in mid-summer 2026

It’s the last week of July, the lake is packed with boats, and you’d think buyer interest around Lake Minnetonka would be cooling off along with the crowds after Labor Day. It isn’t. Lake Minnetonka real estate is still moving at a pace that’s catching a lot of house hunters off guard this mid-summer, with tight inventory, rising prices, and sellers still holding the upper hand across most price points. If you’ve been telling yourself you’ll “wait until fall when things calm down,” the numbers suggest that plan needs a second look.

Where Lake Minnetonka Prices Stand This July

Depending on which slice of the market you’re looking at, the numbers vary — which is exactly why it’s worth using ranges instead of a single headline figure. Across the broader Lake Minnetonka region, median sales prices have recently landed in the $790,000 to $835,000 range, up roughly 6% in a single month and closer to 14% over the trailing twelve months, according to Redfin’s market data. That range alone tells you Lake Minnetonka real estate isn’t a single market — it’s several overlapping ones. Move into the true waterfront segment — homes with actual lake frontage or association access — and the range widens dramatically, with average sale prices in 2025 landing around $1.08 million and active luxury listings currently averaging closer to $2.8 million, or roughly $545 per square foot. In plain terms: the “typical” Lake Minnetonka home and the “trophy” Lake Minnetonka home are two very different conversations, and buyers need to know which one they’re shopping in before they start comparing listings.

Why Inventory Still Isn’t Loosening Up

Months of supply around the lake has been sitting in the 3.6 to 3.8 range recently — well under the 5 to 6 months that typically signals a balanced market. That’s a structural issue, not a seasonal blip: shoreline simply doesn’t get created, and the towns that ring Lake Minnetonka (Wayzata, Excelsior, Deephaven, Orono, Tonka Bay, Mound, and the rest) have been supply-constrained for years. New listings have ticked up slightly, and homes are sitting a bit longer than they were a year ago — days on market have stretched into the 60s and 70s in some pockets, up from the high 50s — but longer marketing time hasn’t translated into pricing power for buyers. Sellers are still fielding offers close to asking price, with recent data showing homes selling for roughly 95% of list price on average. Slower doesn’t mean softer — it’s one more sign that Lake Minnetonka real estate is holding its ground even in the slower part of the summer calendar.

What Mortgage Rates Mean for Buyers Right Now

The 30-year fixed rate has been hovering in the mid-6% range through July 2026, landing at 6.58% as of the most recent Freddie Mac Primary Mortgage Market Survey — down noticeably from about 6.74% a year earlier. That’s not a dramatic swing, but for a $1 million-plus lake purchase, even a quarter-point of movement changes the monthly payment by hundreds of dollars. Buyers who locked in financing earlier this summer, or who are working with a lender tracking rates closely, are in a better negotiating position than those still shopping for a mortgage and a house at the same time. This is one more reason serious buyers around Lake Minnetonka aren’t sitting on the sidelines waiting for a “better time” — rate movement this year has rewarded people who stay engaged, not people who pause.

Which Lake Towns Are Seeing the Most Activity

Activity isn’t evenly spread across the lake. Wayzata continues to draw buyers who want walkable downtown access alongside water views, and its bay-facing properties are commanding some of the strongest per-square-foot numbers on the lake. Excelsior is pulling in buyers who want more small-town charm and a shorter commute into the western metro. Deephaven and Tonka Bay are seeing steady interest in their mix of historic cottages and newer builds, while Mound, Spring Park, and Greenwood remain the more accessible entry points for buyers who want lake access without a waterfront price tag. If you’re weighing a couple of these towns against each other, our Lake Minnetonka community page breaks down more of what makes each pocket of the lake different.

Should You Keep Shopping Through August?

If you’re serious about Lake Minnetonka real estate, mid-summer isn’t the lull people assume it is. Inventory is tight, well-priced homes are still fielding competitive offers, and mortgage rates aren’t guaranteed to sit still. The buyers who are winning right now tend to have two things in common: they know exactly which price band and which town they’re targeting, and they’re working with an agent who has real, current knowledge of that specific stretch of shoreline — not just general Twin Cities market experience. Reliable neighborhood-level data is also available through resources like Minnesota Housing if you want to look at financing programs alongside your search.

Lake Minnetonka’s market rewards buyers who move with good information and the right local partner. MinnMatch connects you with a vetted local agent who knows this stretch of shoreline — its towns, its price bands, and its pace — so you’re not guessing your way through a competitive summer market. Curious how the matching process works? See how MinnMatch works.

HOA or No HOA? What Minnesota Buyers in 2026 Need to Know Before Making an Offer

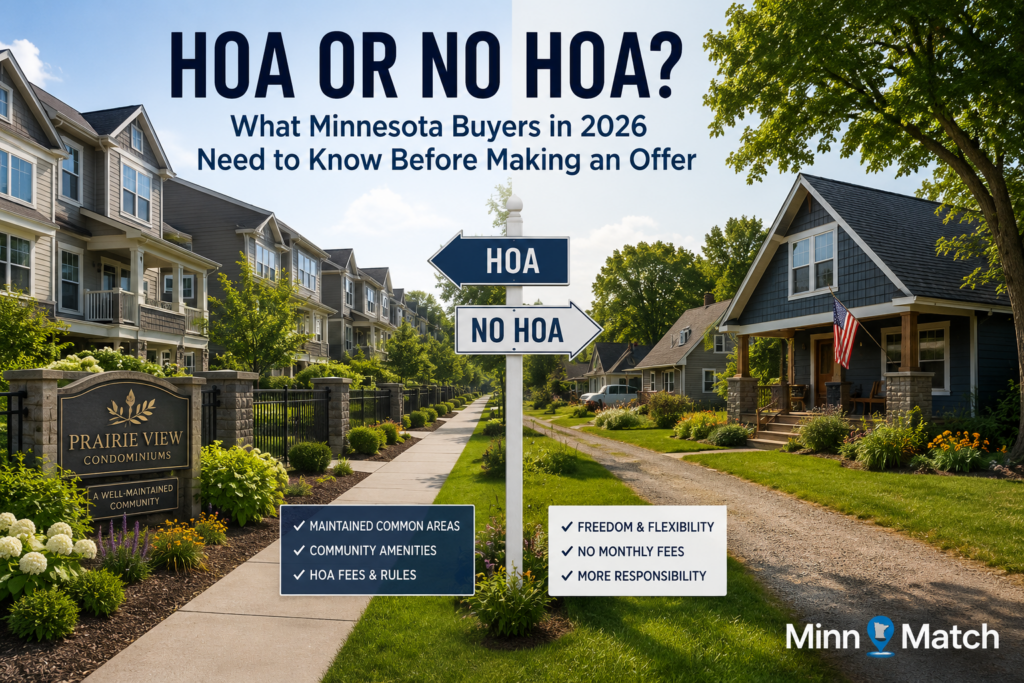
Split graphic comparing HOA townhome community and non-HOA single-family home with a signpost pointing each direction

You found the layout you want, the price feels right, and then the listing mentions it: HOA. For a lot of Twin Cities buyers, that one line raises more questions than it answers. Is an HOA in Minnesota a dealbreaker, a convenience, or just part of the territory once you start touring townhomes and condos? The honest answer is “it depends” — but 2026 is actually a meaningful year to be asking, because Minnesota just overhauled the law that governs how an HOA in Minnesota operates. Here’s what buyers need to understand before writing an offer.

What an HOA in Minnesota Actually Is (And Who It Governs)

Most homeowners associations in Minnesota — whether attached to a townhome, condo, or single-family planned community — fall under the Minnesota Common Interest Ownership Act, commonly shortened to MCIOA. This is the state law that has applied automatically to common interest communities created after June 1, 1994, and it sets the ground rules for how an HOA collects dues, manages shared property, and communicates with owners. Older associations aren’t automatically covered, though many have voluntarily opted in over the years. If a property you’re considering has an association, that association almost certainly answers to MCIOA, and understanding the basics of that law is one of the more useful things a Minnesota buyer can do before making an offer.

In practice, an HOA takes on responsibilities you’d otherwise handle yourself: exterior maintenance, landscaping, snow removal, insurance on shared structures, and upkeep of amenities like pools or clubhouses. In exchange, you agree to pay dues, follow the community’s rules, and accept that some decisions about your building or block are made collectively rather than individually. For buyers weighing a lower-maintenance lifestyle against wanting full control of their property, that trade-off is really the heart of the HOA question.

What an HOA in Minnesota Actually Costs You Each Month

This is where buyers are often caught off guard, and the numbers vary enough that a single figure would be misleading. Metro-wide reporting on 2025 sales put the median HOA fee across the Twin Cities at roughly $278 a month — a notably higher share of the typical house payment than most U.S. metros see. Townhome-specific associations in the metro tend to run higher than that median, commonly landing somewhere in the $300–$450 range, especially in communities with more shared amenities. Condo dues can climb well beyond that: buildings with elevators, structural reserves, or full-service amenities have pushed some Twin Cities condo fees close to $1,000 a month.

Because the range is this wide, don’t anchor to a single “average” when you’re evaluating a specific property. Ask for the association’s most recent financials and reserve study, and look at the trend over the past three to five years, not just the current monthly number. A fee that looks reasonable today can jump significantly if the association has been underfunding its reserves — which is exactly the kind of risk Minnesota’s new rules are trying to catch earlier.

Minnesota’s New HOA Rules: What Changed in 2026

2026 is a genuinely important year for anyone buying into a homeowners association here. Minnesota lawmakers passed a significant update to MCIOA this session — sometimes referred to as an HOA “bill of rights” — with most provisions set to take effect January 1, 2027, giving associations roughly seven months to come into compliance. Buyers closing between now and then should know the changes are coming, because they’ll shape how the association you’re joining operates going forward.

Among the more buyer-relevant pieces: associations will face new transparency requirements around board meetings and documents, competitive-bidding rules for larger maintenance contracts, limits on fines, added protections against retaliation, and a streamlined process for terminating an HOA under certain conditions. Existing MCIOA requirements already in place include annual financial statements (with a CPA review unless owners waive it), reserve fund reviews at least every three years, and a resale disclosure certificate that sellers must provide when a unit changes hands. That resale certificate is one of the single most useful documents a buyer can request — it typically spells out current dues, any pending special assessments, and the financial health of the association.

The state’s Department of Commerce keeps current guidance on MCIOA and common interest communities, and it’s worth a look if you want the details straight from the source rather than secondhand. You can find that at the Minnesota Department of Commerce’s common interest community resource page.

HOA or No HOA: How to Decide What’s Right for You

There’s no universally right answer here — it comes down to what kind of homeowner you want to be. An HOA can be a genuinely good fit if you travel often, want predictable (if sometimes pricier) monthly costs instead of surprise repair bills, or specifically want amenities like a pool, fitness room, or maintained common grounds without personally managing any of it. Nationally, homes in HOA communities have tended to carry a modest price premium over similar non-HOA homes, which some buyers see as a sign the arrangement holds resale value — a data point tracked at the national level by the U.S. Census Bureau’s housing statistics.

On the other side, if you want full control over your landscaping, exterior paint color, or whether you can park a boat in the driveway, an association’s rules can feel restrictive fast. And as Twin Cities condo owners have learned recently, rising dues can make a property harder to resell, particularly at the entry-level price point where buyers are most fee-sensitive. If you’re comparing a specific HOA property against a non-HOA alternative, it often helps to look at recent comparable sales and neighborhood context — resources like Redfin’s neighborhood and market data can be useful for that kind of side-by-side comparison, alongside whatever your agent pulls directly from the MLS.

Whichever direction you lean, read the governing documents before you write an offer — not after. Declarations, bylaws, rules, and the most recent meeting minutes will tell you far more about day-to-day life in that community than the listing sheet ever will.

Getting the Right Guidance for Your Situation

HOA questions are exactly the kind of thing that benefit from someone who knows the specific building, block, or association you’re considering — not just general rules of thumb. A Twin Cities agent who regularly works in a given community will already know which associations are well-run, which have had special assessments, and which fee ranges are typical for that neighborhood. If you’re weighing an HOA property and want that kind of on-the-ground read before you make an offer, MinnMatch can match you with a local agent who’s handled exactly this kind of decision before.

Edina MN Summer 2026: The Luxury Market Heats Up — What Buyers Are Looking For

Large stone luxury home in Edina, MN with manicured landscaping and hydrangeas

Summer in Edina usually means one thing for real estate watchers: the luxury end of the market wakes up. Buyers who spent the spring touring quietly start writing offers, sellers who waited for peak curb appeal finally list, and the upper price tiers start moving at a pace the rest of the Twin Cities doesn’t see. This year is no exception. Edina luxury real estate is having a genuinely active summer, with prices, competition, and buyer expectations all climbing at once. If you’re watching this market from either side of the transaction, here’s what’s actually happening and what it means for you.

Edina Luxury Real Estate: Where the Market Stands This Summer

The topline numbers tell the story. Edina’s median sale price across all home types reached roughly $700,000–$715,000 as of the most recent Redfin data, up nearly 7% from a year ago — one of the stronger year-over-year gains among western metro suburbs. That’s the citywide median, not the luxury segment specifically, which gives you a sense of how much the upper tiers are pulling the average upward.

Zoom out to the broader Twin Cities picture and Edina’s premium becomes clearer. Regionwide, the Minneapolis Area Realtors monthly reports have shown the 16-county median sales price sitting in the $390,000–$410,000 range this year, with inventory and new listings both up compared to last summer. Edina is running well above that baseline, which is typical — but the gap has been widening in 2026, a sign that high-end buyers are more active right now than buyers in the broader market.

Because Edina’s luxury segment is a relatively thin slice of total sales, it’s worth treating any single-month figure as a range rather than a precise number — a handful of high-dollar closings can swing a monthly average significantly. The consistent theme across sources, though, is upward pressure on price and continued buyer interest at the top of the market.

Why Prices Keep Climbing in Edina

A few forces are working together here. Edina’s school district reputation continues to be one of the single biggest draws for move-up families, and that demand doesn’t soften much with rate changes — buyers who want in tend to stretch to make it work. At the same time, the supply of true move-in-ready luxury inventory in established neighborhoods stays tight, since many of Edina’s most desirable streets are largely built out, with turnover happening only when longtime owners decide to sell.

Layer on the fact that summer is simply peak shopping season — more inventory hits the market, but more buyers are also actively touring, comparing, and competing for it. In a market like Edina’s, where Edina luxury real estate buyers often have specific, non-negotiable criteria (school boundary, lot size, proximity to certain amenities), that competition concentrates around the same small pool of qualifying homes rather than spreading evenly across listings.

What Luxury Buyers Are Actually Looking For Right Now

Buyer priorities in this segment have shifted somewhat over the past couple of summers. Move-in-ready condition is worth more than it used to be — with financing costs elevated, fewer buyers want to take on a major renovation on top of a jumbo mortgage payment. Homes that already have updated kitchens, primary suites, and mechanical systems are commanding real attention and moving faster than comparable homes that need work.

Outdoor living space has also become a bigger differentiator. A well-designed patio, mature landscaping, or a usable backyard is showing up as a genuine selling point rather than a nice-to-have, especially for summer showings when buyers can actually picture themselves using the space. Dedicated home office space remains a near-must for a large share of Edina’s buyer pool, many of whom are in hybrid or flexible-schedule roles. And finished lower levels — media rooms, guest suites, home gyms — continue to add meaningful value in this price range, where buyers expect the whole house to feel finished, not just the main floor.

How Financing Fits Into the Picture

Rates matter more at this price point than people sometimes assume. According to Freddie Mac’s Primary Mortgage Market Survey, the 30-year fixed rate has been holding in the mid-6% range through July, recently averaging around 6.58%. Most Edina luxury real estate purchases sit above conforming loan limits, meaning buyers are working with jumbo financing, larger cash reserves, and sometimes different underwriting timelines than a typical conventional buyer.

That’s part of why so many serious Edina luxury real estate buyers this summer are coming to the table with strong pre-approvals or all-cash offers already lined up — in a market where a handful of qualifying homes gets competing offers, financing readiness is often what separates the winning bid from the runner-up.

Working With the Right Agent in a Competitive Market

A market this active rewards preparation and local expertise over general real estate know-how. Whether you’re a buyer trying to move fast on the right home or a seller trying to price a property correctly in a fast-moving upper tier, the agent you work with matters more in Edina’s luxury segment than it does in a more typical price range — pricing mistakes and missed timing are more costly here.

That’s exactly the kind of fit MinnMatch is built to solve. Rather than searching agent directories or picking a name you recognize from a bus bench ad, MinnMatch’s team personally matches you with a vetted local agent who actually knows Edina’s luxury market — its neighborhoods, its price bands, and its buyers. It’s a free service for buyers and sellers alike, and it’s worth understanding how the matching process works before your next move in this market.

Lock Your Rate or Float? What Minnesota Home Buyers Should Know About Mortgage Rates in 2026

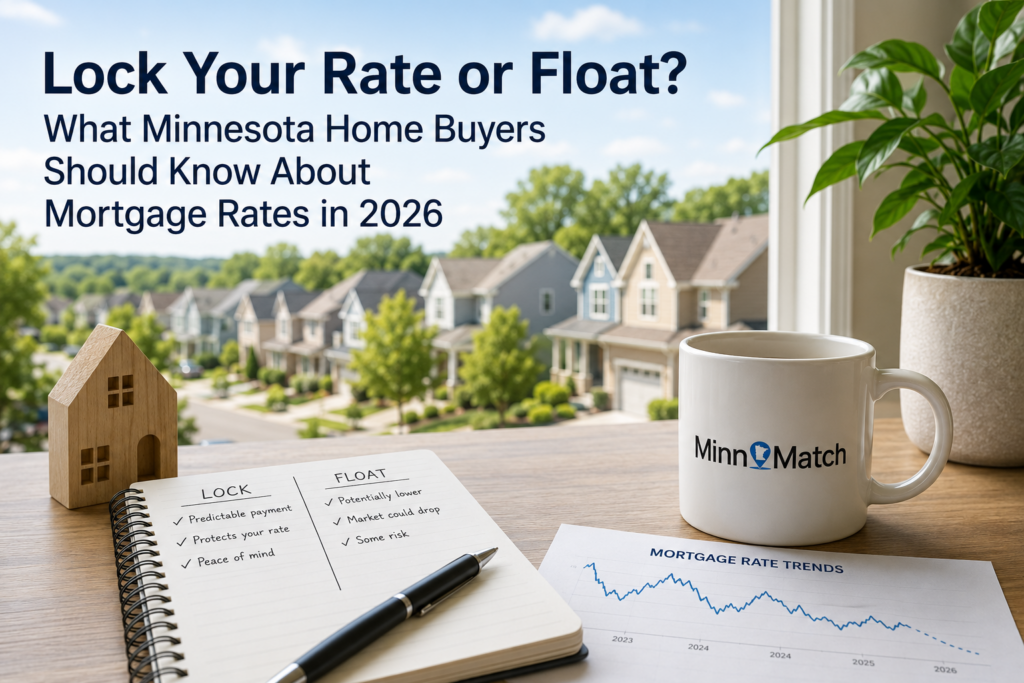
Notebook comparing lock vs. float mortgage rate options with MinnMatch mug and Twin Cities homes

If you’re shopping for a home in the Twin Cities right now, you’ve probably noticed mortgage rates have been anything but boring lately. They ticked up two weeks in a row through late July, and the Federal Reserve’s next meeting could nudge them further in either direction. That leaves a lot of Minnesota buyers asking the same question: should you lock your mortgage rate the moment you get an offer, or float it and hope for a better number before closing? There’s no universal right answer, but there is a smart way to think through it — and that’s what we’re walking through here.

Where Minnesota Mortgage Rates Stand Right Now

As of the most recent Freddie Mac Primary Mortgage Market Survey, the average 30-year fixed rate mortgage sits at 6.58%, up slightly from 6.55% the week before and 6.49% the week before that. Compare that to a year ago, when the 30-year average was running closer to 6.74%, and you can see rates have actually improved a bit over the past twelve months even with this recent upward drift. The 15-year fixed rate, often used by move-up buyers and downsizers here in the Twin Cities, is averaging just under 6%.

What does that mean if you’re house hunting in Eden Prairie, Plymouth, or South Minneapolis this summer? Mostly that rates have been trading in a fairly narrow band for a couple of months, but the direction has tilted upward recently rather than the steady drift downward a lot of buyers were hoping for. That’s exactly the kind of environment where a mortgage rate lock decision actually matters.

Locking vs. Floating: What Each Choice Really Means

A rate lock is an agreement with your lender that guarantees a specific interest rate for a set period — typically 30, 45, or 60 days — while your loan moves through underwriting to closing. Once locked, your rate won’t change even if the broader market moves, whether that’s good news or bad news for you. Most Minnesota lenders don’t charge extra for a standard lock window, though longer locks (say, 90 days for new construction) sometimes come with a small fee or slightly higher rate.

Floating means you’re choosing not to lock yet, betting that rates will drop before you need to commit. Some lenders also offer a “float-down” option, which lets you lock now but still capture a lower rate if one becomes available before closing — usually for an added fee. Floating without any safety net at all is the riskiest version of this strategy, since there’s nothing protecting you if rates move the other direction while you wait.

Why the Fed’s Late-July Meeting Matters for Your Rate Strategy

The Federal Reserve’s Federal Open Market Committee meets July 28-29, and it’s one of the more closely watched meetings of the year for anyone weighing a mortgage rate lock decision. The Fed has held its benchmark rate steady through multiple meetings in 2026, and most market pricing points to another hold this time around, though a modest increase hasn’t been ruled out given persistent inflation. Mortgage rates don’t move in lockstep with the Fed’s overnight rate, but Fed commentary and inflation data both tend to ripple through to the 30-year fixed rate within days.

Practically speaking, if you’re closing on a Twin Cities home in the next few weeks, this meeting sits right in the middle of your process. That’s a strong argument for locking sooner rather than later if you’re already comfortable with today’s rate and don’t want to be surprised by a rate hike mid-transaction. Floating through a Fed meeting is a real bet, not a guaranteed win.

How to Decide: Questions Minnesota Buyers Should Ask

There’s no single formula for the lock-or-float decision, but a few questions tend to clarify it fast:

  • How far out is your closing? The further away, the more time rates have to move — in either direction.
  • Would a small rate increase change whether the home is affordable? If your budget is tight, locking removes that variable entirely.
  • Does your lender offer a float-down option? This can be a reasonable middle ground if you want some downside protection.
  • How do you feel about today’s rate on its own merits? If it works for your monthly payment and long-term plans, waiting for a “maybe” is rarely worth the stress.

If affordability is tight either way, it’s also worth asking your lender whether you qualify for a Minnesota Housing fixed-rate loan program, which can sometimes offer more favorable terms than a standard conventional loan. Most Minnesota loan officers will tell you the same thing: rate locks exist to remove uncertainty, not to time the market perfectly. If today’s rate lets you comfortably afford the home you want, locking it in is rarely a mistake — even if rates dip slightly afterward. Chasing the absolute bottom of the market is a gamble, not a strategy.

Get Rate Guidance From an Agent Who Knows the Twin Cities Market

Mortgage rate decisions don’t happen in a vacuum — they’re tied to your timeline, your target neighborhoods, and how competitive the market is for the home you want. A great local agent will loop in a trusted lender and help you weigh the lock-or-float question against your actual purchase timeline, not just the headlines. That’s exactly the kind of personal guidance MinnMatch was built to provide. Tell us what you’re looking for and where, and we’ll hand-match you with a vetted Twin Cities agent who can help you navigate financing decisions alongside everything else. Find your agent match today, or visit how MinnMatch works to see the process from start to finish.

South Minneapolis Mid-2026: The Neighborhoods Driving the Most Appreciation Right Now

Tree-lined South Minneapolis residential street with historic homes and downtown Minneapolis skyline in the background, MinnMatch branded featured image

Halfway through 2026, South Minneapolis is proving that not all neighborhoods move at the same pace. While the Minneapolis Area Realtors citywide median has crept up only modestly this year, a handful of South Minneapolis pockets are quietly outperforming — and buyers who’ve been house-hunting since spring have probably already noticed it in the multiple-offer situations popping up around Lake Nokomis and along the Longfellow bluff. If you’re weighing where to buy for long-term value, or wondering whether now’s the right time to sell, here’s an honest look at which South Minneapolis neighborhoods are driving the most South Minneapolis appreciation right now — and which ones are still flying under the radar.

Nokomis: Lake Access Is Still the Biggest Appreciation Driver

Nokomis has been one of the more talked-about pockets of South Minneapolis appreciation this year, and the pattern makes sense once you look at what’s driving it. Homes within walking distance of Lake Nokomis or Lake Hiawatha continue to pull a premium, and price-per-square-foot figures for the neighborhood have climbed at a noticeably faster clip than the citywide average, according to Redfin’s Nokomis market data. Median sale prices have bounced around month to month — which is typical for a neighborhood where sales volume is thinner than in the citywide numbers — but the 1920s bungalows and Tudors near Minnehaha Parkway are consistently drawing multiple offers when they’re priced right. If you’re buying here for appreciation potential, the blocks closest to the parkway loop tend to hold their premium best.

Longfellow: Steady, Sustainable Growth Along the River

Longfellow’s appreciation story looks a little different — less of a spike, more of a steady climb. The neighborhood’s proximity to Minnehaha Falls, the river trails, and a walkable commercial strip along E 42nd Street has made it a consistent draw for buyers who want character housing without the price tag of Linden Hills or Fulton. Recent Redfin data for Longfellow has shown the neighborhood posting some of the more reliable year-over-year gains among South Minneapolis submarkets, and homes here are still landing well under $450,000 in most cases — a meaningful gap compared to the lake-adjacent neighborhoods on the city’s west side. That combination of below-median entry pricing and above-average appreciation is exactly what makes a neighborhood worth watching for the next few years, not just this one.

Kingfield: The Walkable Value Play With Momentum

Kingfield doesn’t get talked about as much as its neighbor Linden Hills, but it’s arguably become one of the smarter buys in South Minneapolis for exactly that reason. Prices here have typically run well below the Linden Hills and Fulton corridor for comparable 1920s-1940s housing stock, while still delivering the same walkable dining and tree-lined streets buyers pay a premium for a few blocks west. That price gap has been narrowing over the past several years as more buyers get priced out of the southwest corner and shift their search east — and Kingfield has quietly posted above-average appreciation over that stretch as a result. For buyers who want the “southwest Minneapolis feel” without the southwest Minneapolis price, this is one of the more compelling corners of the market right now.

Powderhorn and the Value Tier: Worth Watching, Not Yet Racing Ahead

Not every South Minneapolis neighborhood is heating up at the same rate, and that’s worth saying plainly. Powderhorn, for example, has had a softer stretch in recent months, with sale prices near the $300,000-to-$325,000 range and less of the appreciation momentum showing up in Nokomis or Longfellow. That’s not necessarily a bad thing for buyers — it means there’s still relative value in a neighborhood with strong park access and an increasingly active local dining and arts scene around Powderhorn Park. Neighborhoods like this tend to move in waves as adjacent areas price buyers out, so it’s one worth keeping on your radar even if it isn’t leading the pack today.

South Minneapolis Appreciation: What It Means If You’re Buying or Selling Right Now

The bigger picture: South Minneapolis appreciation isn’t happening evenly across the map, and generic citywide statistics can hide a lot of what’s actually going on block by block. Understanding where South Minneapolis appreciation is concentrated right now can make a real difference in both your offer strategy and your timeline. That’s exactly the kind of nuance that’s hard to get from a national listing site and easy to miss if you’re not watching the market closely all year. If you’re trying to figure out whether Nokomis, Longfellow, Kingfield, or one of the value-tier neighborhoods makes the most sense for your goals, MinnMatch can connect you with a local agent who works these specific pockets of South Minneapolis every day and can tell you, block by block, where the momentum really is. It’s a free service, and matching you with the right local expert — rather than whoever happens to answer the phone first — is the whole point. Curious how the process works? Here’s a quick look at how MinnMatch matches you with an agent.

Moving to Minnesota from Out of State in 2026: Your Complete Real Estate Survival Guide

Moving truck with "Welcome Home" Minnesota decal parked at a Twin Cities house, skyline across the lake, MinnMatch logo

If you’re moving to Minnesota this year, you’re part of a trend that’s finally reversed after nearly a decade. For the first time since 2018, more people moved into Minnesota from other states than left — and a good number of them are landing right here in the Twin Cities. Whether you’re relocating for a job at one of the metro’s major employers, chasing a lower cost of living than the coasts, or simply ready for a change of scenery, buying a home in an unfamiliar market is a very different experience than buying in your hometown. This guide walks you through what out-of-state buyers need to know about Minnesota real estate in 2026 — from current prices and rates to the paperwork nobody warns you about.

Why People Are Moving to Minnesota Right Now

Minnesota spent years watching more residents pack up for other states than it gained in return. That changed with the most recent U.S. Census Bureau data, which showed a net gain of roughly 8,300 residents from domestic migration between mid-2024 and mid-2025 — the state’s first positive domestic migration total since 2018. It’s a modest number in the grand scheme, and it doesn’t erase the tens of thousands of residents Minnesota lost during the pandemic-era exodus to lower-tax, warmer-weather states. But the direction matters. Working-age adults and families relocating for jobs in health care, tech, and manufacturing are a meaningful part of that shift, and many of them are choosing the Twin Cities metro specifically for its job market, school systems, and relative affordability compared to the coasts.

If you’re relocating to Minnesota from a higher-cost state, you’ll likely notice the difference immediately in what your budget buys. That said, don’t assume Minnesota is uniformly cheap — some Twin Cities suburbs carry price tags that rival coastal markets, while others offer real value. Understanding those neighborhood-level differences before you start touring homes will save you a lot of second-guessing.

What It Costs to Buy a Home After Moving to Minnesota

As of June 2026, the median home price across the Twin Cities metro sat at roughly $410,000, up about 2 percent from a year earlier, according to Minneapolis Area Realtors data. Statewide, the median was closer to $375,000. Inventory has also loosened up considerably — the Twin Cities metro ended June with nearly 10,900 homes on the market, a seven-year high for the region, and homes were sitting for an average of about six weeks before selling. That’s a real shift from the frenzied, multiple-offer market of a few years ago, and it means out-of-state buyers arriving in 2026 generally have more room to shop, negotiate, and think before making an offer than buyers did in 2021 or 2022.

Mortgage rates are the other half of the budgeting picture. Freddie Mac’s Primary Mortgage Market Survey put the average 30-year fixed rate at 6.55% in mid-July 2026, with 15-year rates near 5.93%. Rates like these mean it’s worth getting pre-approved before you start touring homes in the Twin Cities, since your budget on paper can shift meaningfully with even a quarter-point move in rate. If you haven’t worked with a Minnesota lender before, ask any agent you connect with locally for a few reputable recommendations — out-of-state pre-approvals from a national online lender don’t always move as smoothly through Minnesota’s closing process as one from a lender who works here regularly.

The Minnesota-Specific Checklist Out-of-State Buyers Miss

Buying a home is only part of relocating to Minnesota — there’s a set of state-specific administrative steps that catch a lot of newcomers off guard:

  • Driver’s license and vehicle registration: New Minnesota residents are required to transfer their driver’s license and register their vehicle in the state within a set window after establishing residency. Plan a trip to Minnesota Driver and Vehicle Services early — it’s rarely a same-day process.
  • Homestead classification: Once you close on a Minnesota home and it becomes your primary residence, apply for homestead classification with your county assessor. It can meaningfully lower your property tax bill compared to a non-homesteaded property, but it isn’t automatic — you have to file for it.
  • Winter prep isn’t optional: If you’re coming from a warm-weather state, budget for real winter gear, a home with a functioning furnace and roof (have both inspected carefully), and — if your new home has one — a driveway and walkway you’re prepared to keep clear from November through March.
  • School enrollment timing: Twin Cities school districts often have enrollment windows and open-enrollment deadlines that run well ahead of the school year. If you’re moving with kids, start that process as soon as you have an address, not after you’ve unpacked.

None of this is meant to be discouraging — it’s simply the paperwork layer that a local agent will walk you through as a matter of course, but that out-of-state buyers often have to piece together themselves.

Choosing Where to Land in the Twin Cities

One of the hardest parts of moving to Minnesota from out of state is that you don’t have decades of local knowledge to draw on when picking a community. Families relocating for schools and space often land in suburbs like Plymouth, Eden Prairie, or Minnetonka. Buyers drawn to lake life and a slower pace tend to look toward Wayzata and the broader Lake Minnetonka area, while those who want walkable urban living gravitate toward neighborhoods in South Minneapolis. If budget is more flexible and top-tier schools and amenities are the priority, Edina consistently draws relocating buyers willing to pay for it.

The honest answer is that no article can tell you which of these fits your life — that’s a conversation, not a checklist. It depends on your commute, your kids’ ages, whether you want a yard or a patio, and how much winter driving you’re willing to do. This is exactly the kind of decision where a few good questions from someone who knows these towns block by block save you months of guessing.

You Don’t Have to Figure Out the Twin Cities Alone

Moving to Minnesota from out of state means buying a home in a market you didn’t grow up watching — you don’t have the neighborhood instincts a local buyer has, and that’s completely normal. That’s exactly the gap MinnMatch was built to close. Instead of searching for an agent and hoping they understand what matters to a newcomer, tell us about your move — your job, your must-haves, your timeline — and we’ll personally match you with a Twin Cities agent who knows the specific communities you’re considering and has helped other relocating buyers navigate the same learning curve. It’s a free service for buyers, and it takes the guesswork out of picking both a neighborhood and an agent at the same time. See how the matching process works, or go ahead and find your Twin Cities agent today.

Edina vs. Eden Prairie in 2026: Prestige, Price & Practicality Compared

Edina vs. Eden Prairie MN suburb comparison — 50th & France district next to Eden Prairie's downtown walkway

If you’re cross-shopping the west metro, you’ve probably landed on the same two names everyone else does: Edina and Eden Prairie. Both show up on every “best suburbs” list in the Twin Cities, both feed into top-rated school districts, and both are a short hop from downtown Minneapolis. But they’re not interchangeable. When you actually compare Edina vs Eden Prairie, the differences in price, pace, and personality are bigger than the “great suburb” label suggests. Here’s how they really stack up in 2026.

Edina vs Eden Prairie Home Prices & Market Pace

This is where the two suburbs part ways the most. Edina carries a premium: depending on the month and data source, Redfin’s Edina market data and local brokerage reports put the median sale price somewhere in the roughly $650,000 to $750,000 range, with homes running $276–$287 per square foot. Eden Prairie is meaningfully more accessible, with medians typically landing in the $450,000 to $530,000 range and a price-per-square-foot closer to $210.

Pace tells its own story, too. Eden Prairie has been running hot, with homes going under contract in roughly three to four weeks and multiple-offer situations common in move-in-ready price bands. Edina homes, especially in the higher price tiers, tend to sit a bit longer — often 28 to 45 days — simply because there’s a smaller pool of buyers who can compete at that price point. Neither market favors a wandering search; both reward buyers who are pre-approved and ready to move when the right listing appears.

According to Minnesota Housing, statewide affordability pressure has pushed more buyers toward mid-priced suburbs, which helps explain why Eden Prairie’s pace has picked up relative to pricier peers. Put plainly: in the Edina vs Eden Prairie price comparison, Edina buys prestige and Eden Prairie buys breathing room in the budget.

Schools: Two Top-Tier Districts, Different Strengths

You genuinely can’t go wrong on schools here — both districts consistently earn A+ overall grades and rank among Minnesota’s top public school districts year after year. Edina Public Schools has long traded on name recognition and a deep bench of AP and IB offerings, while Eden Prairie Schools has climbed statewide high school rankings in recent years, with Eden Prairie High School routinely landing among the state’s top handful of public high schools. If school quality alone is your deciding factor, the Edina vs Eden Prairie comparison is close to a wash — the bigger question is which building, program, or neighborhood elementary feeds into a fit for your kids.

Lifestyle & Character: Polished Prestige vs. Practical Space

Edina’s identity is built around established prestige. The 50th & France retail district, Country Club neighborhood’s tudor-lined streets, Interlachen’s golf pedigree, and Centennial Lakes Park give it a polished, walkable, almost small-city feel packed into a first-ring suburb. It’s the kind of place where move-up buyers pay for character and location as much as square footage.

Eden Prairie leans more practical. You get newer construction, larger lots, and more house for the dollar, plus an outdoor-recreation identity built around Round Lake, Riley Lake, Purgatory Creek Park, and an extensive trail network. It’s a suburb built for families who want space to spread out — a three-car garage, a finished basement, a backyard for the dog — without sacrificing the school quality or the commute.

Commute & Location: What “Convenient” Really Means in Each Suburb

Edina’s edge here is real but modest: it sits just southwest of Minneapolis, with a downtown commute of roughly 15 minutes and equally quick access to the MSP airport. Eden Prairie adds a few more minutes to that same downtown drive, but it makes up for it with proximity to its own dense job base — Optum, Starkey, and a growing cluster of corporate campuses along the Highway 212 and 169 corridors mean plenty of Eden Prairie buyers aren’t commuting downtown at all. If your job is in the southwest suburbs rather than the city core, Eden Prairie’s location may actually be the more convenient one.

So, Which Suburb Is Right for You?

There’s no wrong answer between Edina and Eden Prairie — just a different set of priorities. If walkable prestige, established character, and the shortest possible commute to downtown top your list, Edina is worth the premium. If you want more space, newer construction, and a lower buy-in with schools that rival Edina’s, Eden Prairie deserves a serious look.

The honest truth is that the “right” choice depends on details a spreadsheet can’t capture — which streets flood the market with listings, which elementary boundary your dream house actually falls into, which neighborhoods are quietly trending up. That’s exactly the kind of local, on-the-ground knowledge a MinnMatch-matched agent brings to the table. Instead of guessing between two great suburbs, tell us what matters most to your family, and we’ll connect you with a Twin Cities agent who specializes in exactly that trade-off. Curious how the matching works? Here’s how it works — it’s free, human-powered, and built for exactly this kind of decision.